Speak with a licensed insurance agent

1-888-891-0229

Hospital Indemnity Insurance Washington: OIC Rules, Filed Plans and Rates

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 12, 2026

Hospital indemnity insurance in Washington is a fixed-payment policy, regulated by the Office of the Insurance Commissioner (OIC), that pays you a set dollar amount when you are confined in a hospital, no matter what the hospital charges. State law requires every applicant to get a standard disclosure form saying the coverage is not comprehensive and will not pay for most hospital and medical services.

Evergreen State plans

Price Hospital Cash Plans for a Washington ZIP Code

From Spokane to Seattle, see daily benefits filed for your area.

Plan availability, eligibility, and benefits vary by state and policy.

This page is about Washington State. Washington National is an Indiana-based insurer that shares the name and sells hospital plans too, but its name has nothing to do with where you live. For plan design basics, read our overview of hospital indemnity insurance plans.

Below: the Washington statutes and WAC sections behind these policies, plans with Washington paperwork side by side, published Washington premiums and an OIC company check. To price coverage, compare hospital indemnity insurance from several companies in one place.

First things first

Washington allows hospital indemnity insurance as a limited, fixed-payment supplement, sold to individuals and through employers. It pays cash per admission or per day, it is not health insurance, and it does not count as minimum essential coverage under the Affordable Care Act.

What a Hospital Day Costs in Washington

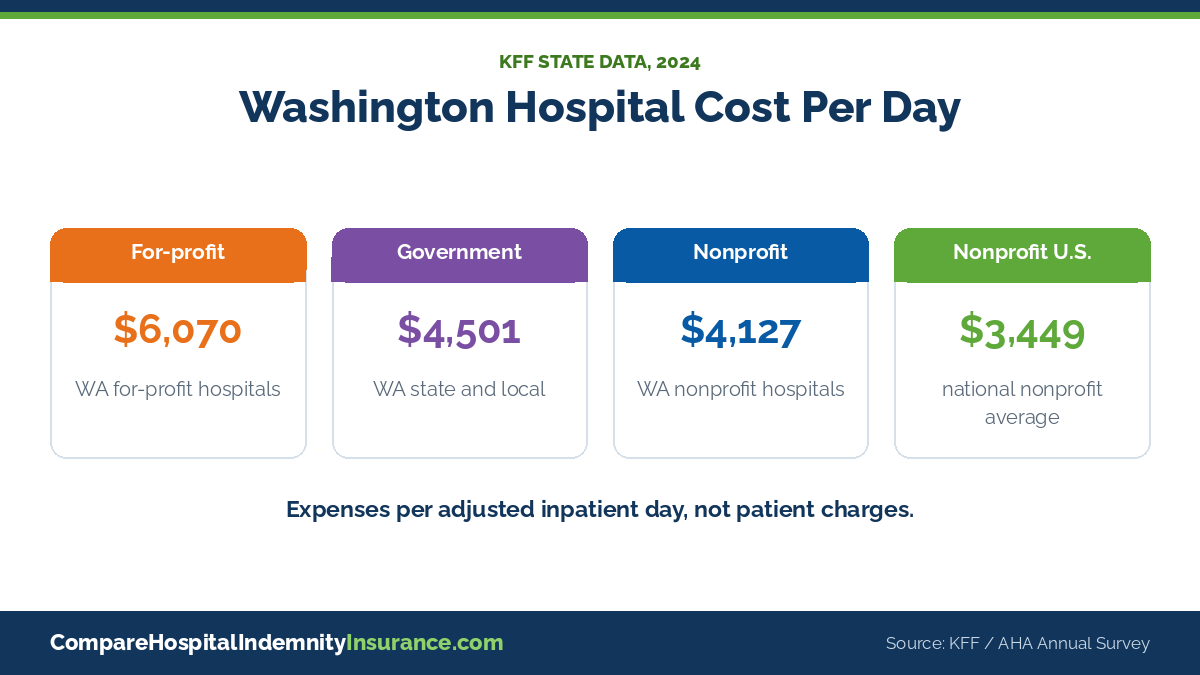
Hospitals in Washington cost more to run per patient day than the national average. KFF, using the American Hospital Association’s annual survey, puts expenses across all Washington hospitals at $4,251 per adjusted inpatient day in 2024, against $3,297 nationally. These are expense estimates, not what a patient is charged.

Example only:

Picture a four-day stay under a plan paying $200 a day for up to six days. The policy sends you $800. That can cover part of a deductible, a hotel room for family driving in from Yakima, or wages lost while you recover.

Cards showing Washington hospital expenses per adjusted inpatient day by ownership type for hospital indemnity insurance Washington shoppers

The Washington Rules Behind Every Policy

Washington regulates these products under its disability insurance laws: chapter 48.20 RCW for individual policies, chapter 48.21 RCW for group plans and the OIC’s rules in chapter 284-50 WAC. Four numbers sum up what matters most to a buyer.

Washington standards at a glance
$10
minimum daily benefit for individual hospital confinement indemnity (WAC 284-50-345)
31 days
minimum days per period of confinement under the same rule
10 days
to return an individual policy for a premium refund (RCW 48.20.013)
30 days
advance filing with the OIC for fixed-payment marketing materials (RCW 48.20.550)

The $10 floor is low, so the 31-day rule matters more. LifeSecure’s Washington plan, for example, adds $15 a day up to 31 days per confinement after your chosen days run out. The return right counts too: an individual policy sent back within ten days of delivery is treated as never issued, and a refund later than 30 days carries a 10% penalty. Group certificates can differ; Cigna’s Washington group summary lists a 30-day right to examine.

The Disclosure Form Washington Requires

Since 2007, RCW 48.20.550 (individual) and RCW 48.21.370 (group) have directed the commissioner to set a standard disclosure form for illness-triggered, hospital confinement and other fixed payment insurance. WAC 284-50-440 spells it out. You must get it when the policy is offered and when you fill out the application, and the insurer must be able to prove delivery.

What the Washington form has to include
  • ✔
    The heading IMPORTANT INFORMATION ABOUT THE COVERAGE YOU ARE BEING OFFERED, in type no smaller than 10 point.
  • ✔
    A plain statement that the coverage is not comprehensive and will not cover most hospital and other medical services.
  • ✔
    Coverage type, benefit amounts, payment triggers, waiting periods, benefit duration and renewability.
  • ✔
    Every exclusion and limitation, including any pre-existing condition clause.
  • ✔
    A caution telling people with a high deductible plan and health savings account to check with an advisor first.

Filed materials show the form in use. Aflac’s Washington disclosure for its accident plan carries that heading, says the Washington State Insurance Commissioner requires it and points Medicare-eligible readers to the federal Medicare insurance guide. Cigna’s Washington group summary adds that the coverage does not satisfy the Affordable Care Act’s individual mandate.

Russell Noga, licensed insurance agent

Disclosure-form check

Washington law requires the standard disclosure form at the time of solicitation and again when the application is completed. If an agent or website moves to the application without that one-page notice, the sale skipped a step the OIC requires, and the form is also the quickest place to find the waiting period and the full exclusion list.

Russell Noga, Licensed Insurance Agent

Plans With Washington Paperwork, Side by Side

We built this table only from documents marked for Washington: state-coded brochures, rate sheets and Washington employer summaries. Carriers without Washington-specific terms in writing were left out.

Carrier (issuing company) How it is sold Hospital stay benefits shown Waiting and pre-existing terms Washington document
LifeSecure (LifeSecure Insurance Company) Individual policy, issue ages 18 through 85, guaranteed renewable for life $100 to $900 a day in $10 steps for 3, 6, 10 or 21 days, then $15 a day up to 31 days per confinement Pre-existing condition care not paid unless it begins more than 6 months after the effective date Policy series LS-HI4-0004 WA brochure and rate sheet
Aflac (American Family Life Assurance Company of Columbus) Hospital Advantage, HSA-compatible, policy series A49000; issue ages not stated $1,500 to $3,000 per confinement in $500 steps, plus $50 a day up to 365 days and $50 a day in ICU up to 30 days 12-month look-back and 12-month pre-existing wait; 30-day sickness wait for people added later Brochure A49H75WA, dated 9/24
MetLife (Metropolitan Life Insurance Company) Group plan through Lewis County, Low and High options Admission $500 or $1,000, up to 4 per year; $100 or $200 a day up to 31 days per confinement Summary says a pre-existing limit may apply to sickness benefits Lewis County benefit summary, coverage effective 1/1/2026
Cigna (Life Insurance Company of North America) Group plan for a Washington employer, Plan 1 Admission $1,250 once every 90 days; stay $100 a day up to 30 days; ICU $200 a day Benefit waiting period: none; 30-day right to examine Washington state benefit summary, form GHIP-00-1000.WA, dated 08/17

Sources: LifeSecure Washington brochure, plan-at-a-glance and monthly rate sheet; Aflac brochure A49H75WA; Lewis County, Wash. MetLife hospital indemnity summary; Cigna Washington state benefit summary (an older 2017 employer document). Group terms are set by each employer. Not shown: UnitedHealthcare’s UHOne site lists hospital indemnity for Washington but names no insurer or terms, and Washington National’s guide confirms only that its portability feature is not offered in Washington.

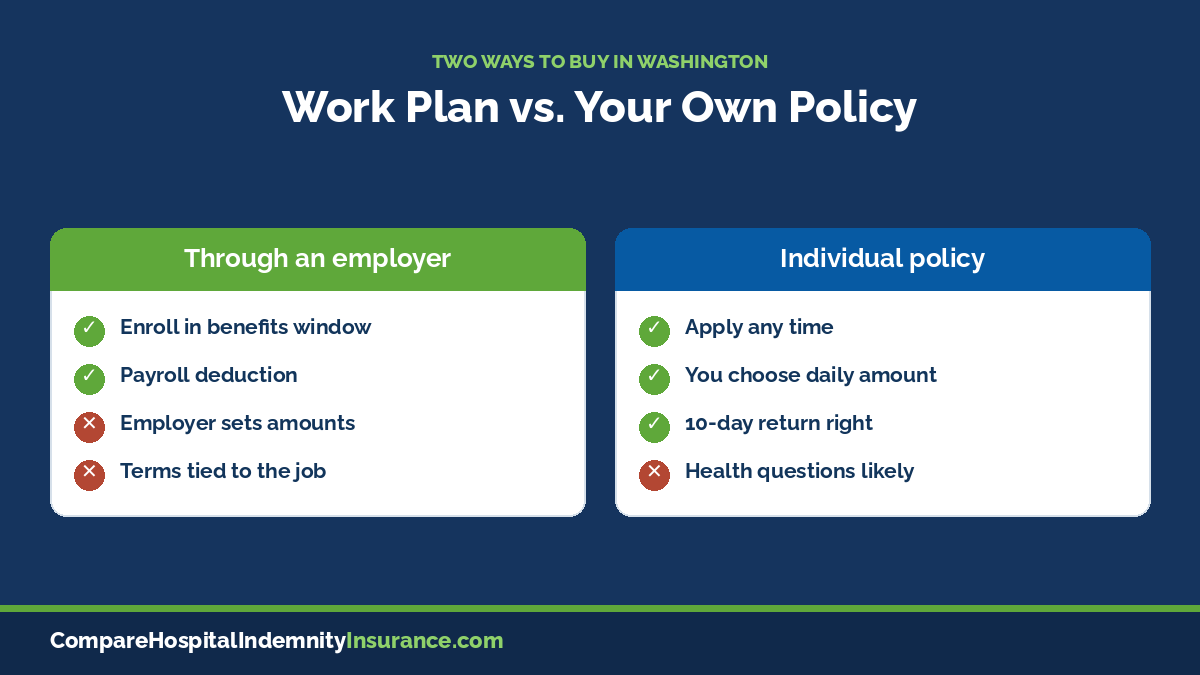
Notice the split. The individual plans let you pick your benefit size and keep the policy if you change jobs, while group plans pay amounts the employer chose. For workplace versions, see our guide to voluntary hospital indemnity insurance.

Comparison of buying hospital indemnity insurance Washington residents get through an employer versus an individual policy

Published Washington Premiums From One Filed Plan

Few insurers post state rates publicly. LifeSecure does, so its Washington rate sheet offers a real starting point. Below are monthly premiums for the policyholder alone, with no riders, as printed.

Issue age band $200 a day, 6 days $500 a day, 6 days
18-29 $8.30 $13.54
30-39 $8.98 $15.37
40-49 $10.28 $20.84
50-59 $13.15 $31.33
60-64 $14.84 $33.35
65-69 $17.33 $40.67

Source: LifeSecure Hospital Indemnity 4.0 Monthly Rates, Washington (form LS-HI4-0306 M WA 09/24). Self-only rates; spouse, child and family tiers cost more. Rates are as published and may change.

Reading the numbers

Moving from $200 to $500 a day costs a 30-year-old about $6 more a month, while a 60-year-old pays roughly $18.50 more. The gap between benefit levels widens with age.

Group premiums are priced across the employer’s workforce instead. Cigna’s 2017 Washington summary showed $10.89 a month for the employee alone. Our hospital indemnity insurance cost guide covers what else moves a quote.

Hospital Indemnity Quotes

Call a Licensed Agent Now

Licensed agents can pull the Washington version of a plan and its disclosure form.

☎ 1-888-891-0229

No obligation to enroll

Where Hospital Indemnity Fits Next to Washington Healthplanfinder

Washington runs its own marketplace, Washington Healthplanfinder, which sells Cascade Care plans: standardized Cascade plans and Cascade Select, the state’s public option. Households up to 250% of the federal poverty level may qualify for Cascade Care Savings on silver or gold Cascade Care plans. Open enrollment for 2027 coverage runs November 1, 2026 through January 15, 2027.

What a Healthplanfinder plan does
✔

Pays hospitals and doctors under a network contract
✔

Counts as minimum essential coverage
✔

Can come with federal and state premium help
What a hospital cash policy does not do
✕

It is not sold as a Healthplanfinder health plan
✕

It does not count as minimum essential coverage
✕

It does not pay providers; the cash goes to you

Order matters. Pick major medical first, through Healthplanfinder, Apple Health if you qualify, or work. Then consider a hospital cash policy to soften the deductible that plan leaves. HSA owners should read the HSA caution on the Washington disclosure form and choose an HSA-compatible design.

How to Vet an Insurer Through the OIC

The Office of the Insurance Commissioner runs an online agent and company lookup. It confirms whether a company or agent is licensed in Washington and shows identifying numbers, the kinds of coverage offered, complaints, disciplinary actions and financial statements.

Start with the legal name
Search the company printed on the disclosure form, such as LifeSecure Insurance Company, not the brand in an ad.
Match the NAIC number
The lookup shows WAOIC, NPN and NAIC numbers, which separate look-alike company names.
Review orders and complaints
A separate orders search lists actions the commissioner has taken, including fines.
Know where to go next
The OIC takes consumer complaints online and lets you check the status of one you filed.

Once a company checks out, line up benefits. Our page on how to compare hospital indemnity insurance quotes walks through admission amounts, day limits and riders.


No-cost comparison

Check Filed Washington Plans Before the Disclosure Form Arrives

Compare admission and per-day amounts from licensed insurers.

Plan availability, eligibility, and benefits vary by state and policy.

What Washington Residents Ask About Hospital Indemnity

➤ Does Washington set a minimum benefit for hospital confinement policies?

Yes, for individual policies. WAC 284-50-345 defines hospital confinement indemnity coverage as paying at least $10 a day for at least 31 days in any one period of confinement. Most plans pay well above that daily floor.

➤ How long do I have to cancel a hospital indemnity policy in Washington and get my money back?

For individual policies, RCW 48.20.013 gives you ten days after delivery to return it for a full premium refund. Group certificates may list a different period, such as the 30 days shown in Cigna’s Washington summary.

➤ Can I buy hospital indemnity on Washington Healthplanfinder?

Healthplanfinder sells Cascade Care and other health plans. A hospital indemnity policy is bought separately, from an insurer, an agent or an employer, and it cannot replace a marketplace plan.

➤ Is Washington National the only company selling hospital plans in Washington State?

No. Washington National is a carrier whose brand name happens to match the state. The Washington documents we reviewed came from LifeSecure, Aflac, MetLife and Cigna.

➤ Does a Washington hospital indemnity policy work with an HSA?

It can, if the plan is designed to be HSA-compatible, like Aflac’s Hospital Advantage version. The Washington disclosure form tells HSA owners to confirm with a tax or benefits advisor before buying.

Free Plan Comparison

Call a Licensed Agent Now

Compare daily hospital benefits from insurers licensed in Washington State.

☎ 1-888-891-0229

No obligation to enroll

Russell Noga, licensed insurance agent

About the Author: Russell Noga

Russell Noga is a licensed insurance agent and the founder of ZRN Health & Financial Services, LLC. He has helped people compare health and supplemental insurance for more than 16 years and reviews every page on Compare Hospital Indemnity Insurance before it is published. Learn more about us or read our Editorial Standards.

CompareHospitalIndemnityInsurance.com is operated by ZRN Health & Financial Services, LLC, a Texas limited liability company based in Austin, Texas. We are not connected with or endorsed by any government agency.