Speak with a licensed insurance agent

1-888-891-0229

Blue Cross Blue Shield Hospital Indemnity: Which Blue Plans Sell It and Where

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 9, 2026

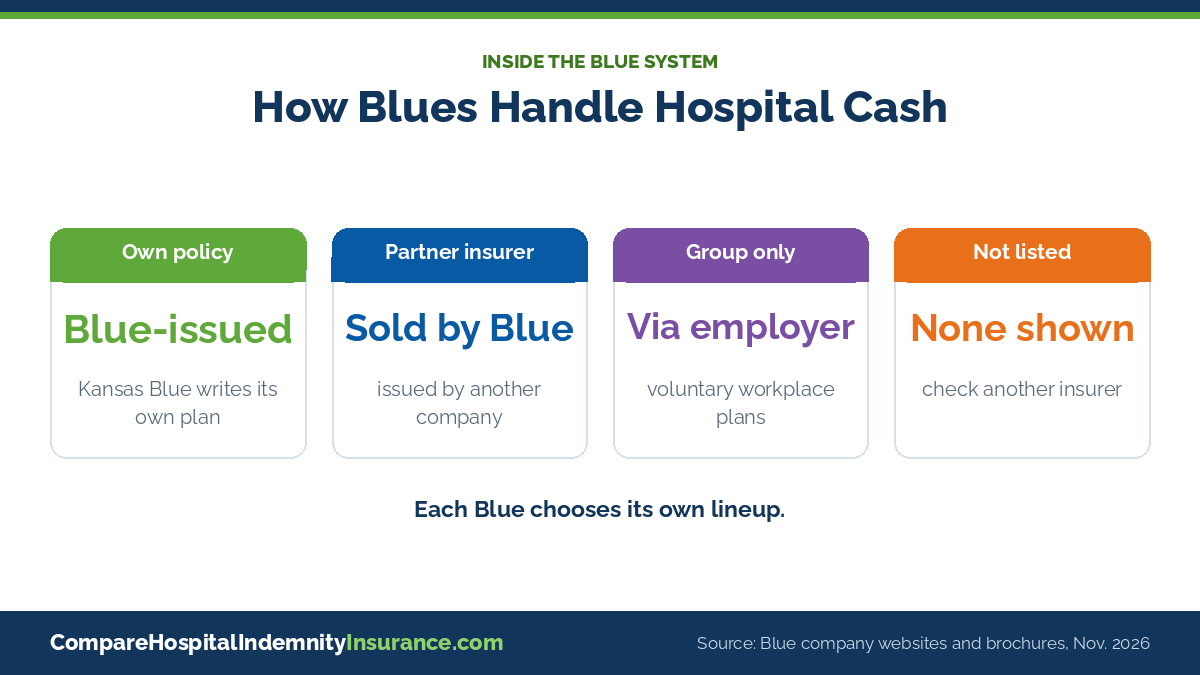
Blue Cross Blue Shield hospital indemnity coverage is sold by some Blue companies, not by Blue Cross Blue Shield as a whole, so whether you can buy it depends on the state you live in and the local Blue that serves it. Some Blues issue their own hospital cash policy, others sell a plan underwritten by a partner insurer, and many list none at all.

State-by-state quotes

Check Hospital Cash Plans Sold Where You Live

Enter your ZIP to see hospital indemnity options, Blue and non-Blue, in your state.

Plan availability, eligibility, and benefits vary by state and policy.

The Blue Cross and Blue Shield Association describes itself as a system of 33 independent, community-based and locally operated companies. Each one decides its own supplemental lineup. This guide lines up the Blue plans that publish hospital indemnity details, shows how to check your own Blue, and explains how a fixed cash plan fits next to Blue medical coverage. For carriers outside the Blue system, see our list of hospital indemnity insurance companies, or compare hospital indemnity insurance quotes for your ZIP code.

The short answer

There is no single national Blue Cross Blue Shield hospital indemnity plan. Several Blue companies, including Anthem, Blue Cross and Blue Shield of Kansas, Blue Cross and Blue Shield of Nebraska, Florida Blue and Blue Cross and Blue Shield of Texas, publicly list hospital indemnity coverage, often issued by a partner insurer and with rules that differ from state to state.

Why Blue Cross Blue Shield Has No One Hospital Plan

The Blue Cross and Blue Shield name is licensed by an association to separate companies. Each licensee runs its own territory, sets its own medical plans and chooses whether to offer extras such as dental, life, cancer or hospital cash coverage. A Blue in one state can sell a hospital indemnity policy while the Blue next door sells nothing of the kind.

The Blue system at a glance
33
independent, locally operated Blue companies
118 million
members, as stated by the association
50 + DC + PR
where Blue companies provide coverage
Blue Cross Blue Shield hospital indemnity: three ways Blue companies sell hospital cash coverage, plus Blues that list none

Blue Companies That Publish Hospital Indemnity Details

We checked Blue company websites, brochures and partner insurer documents in November 2026. The table includes only Blues that publicly name a hospital indemnity or hospital confinement product, and every benefit detail comes from the company’s own page or the issuer’s brochure. Blank spots mean the detail is not published.

Blue company Who can buy Product and issuer One verified detail
Anthem Blue Cross and Blue Shield Individuals; not sold in Connecticut or Virginia Hospital Indemnity Insurance, issued by LifeSecure Insurance Company Issue ages 18 to 85; daily benefit chosen from $100 to $900 in $10 steps
Blue Cross and Blue Shield of Nebraska Individuals in Nebraska Same LifeSecure Hospital Indemnity Insurance design No medical questions for ages 64.5 through 66; simplified underwriting at other ages
Blue Cross and Blue Shield of Kansas Individuals and employees; Kansas except Johnson and Wyandotte counties Secure Hospital Indemnity Plan, issued by the Kansas Blue itself $50 a day for days 1 to 3, then $200 a day through day 365
Florida Blue Individuals and families; employers with 51 or more workers Hospital Indemnity Plans (individual) and Hospital Confinement (group), offered by USAble Life Guaranteed renewable; rates do not rise with age after the effective date
Blue Cross and Blue Shield of Texas Employer groups Supplemental Health (accident, critical illness, hospital indemnity), issued by Dearborn Life Insurance Company Medical and supplemental claims are reviewed together to flag cash benefits
Independence Blue Cross (southeastern Pennsylvania) Employer groups; 25 or more employees at the 2016 launch Hospital indemnity issued by Guardian Life Guaranteed issue and portable after leaving the job, per the launch release

Our review of Blue company pages and issuer brochures, November 2026. Availability and terms change; the outline of coverage or certificate for your state controls. Blues not listed may still sell a plan through employers without publishing details.

What the table shows

Only one of the six, the Kansas Blue, issues its hospital plan under its own name. The rest rely on a partner or affiliated insurer, so the policy you buy may carry LifeSecure, USAble Life, Dearborn Life or Guardian on the cover page.

Russell Noga, licensed insurance agent

Plan-finder tip

A hospital cash policy sold under a Blue logo is often issued by a different insurer, such as LifeSecure, USAble Life, Dearborn Life or Guardian. The issuer named in the brochure disclaimer is the company that receives claims, sets renewal rates and must be licensed in the buyer’s state, so that name belongs on any comparison list next to the Blue brand.

Russell Noga, Licensed Insurance Agent

Two Blue-Sold Designs, Side by Side

The two individual designs with the most published detail work in opposite ways: a fixed Kansas schedule with guaranteed acceptance, and a build-your-own LifeSecure plan with health questions.

Kansas Secure Hospital Indemnity Plan

  • Pays $50 a day for the first three hospital days and $200 a day from day 4 through day 365, counting the day of discharge
  • Accident admissions pay $200 a day from day 1; intensive care or coronary care pays $400 a day
  • A condition diagnosed, treated or advised on in the 90 days before coverage starts is excluded until 365 days have passed
  • Monthly rates printed in the current brochure start at $3.23 for an individual under 30

Easy to miss:

The Kansas brochure says acceptance is guaranteed only for applicants enrolled in minimum essential coverage, meaning the cash plan is meant to sit on top of real health insurance. Residents of Johnson and Wyandotte counties are outside the Kansas Blue’s service area and cannot buy it.

LifeSecure Hospital Indemnity Insurance

  • ✔
    Hospital confinement days of 3, 6, 10 or 21 per stay, with the count resetting after 60 days out of the hospital
  • ✔
    Optional lump-sum admission rider of $500 or $1,000, once per calendar year
  • ✔
    Mental health inpatient benefit of $150 a day for up to 7 days a year
  • ✔
    Pre-existing conditions treated in the 12 months before the start date are excluded for the first 6 months
  • ✔
    Guaranteed renewable for life; the Anthem brochure states there is no ownership tie between LifeSecure and Anthem

How to Find Out If Your Blue Sells a Hospital Plan

Because each Blue sets its own lineup, the reliable route is to check the company that serves your address, not a national site.

1
Name your local Blue. Your medical ID card shows the exact Blue company. If you do not have Blue coverage, the association’s site lists the Blue for each state; a few states, such as Pennsylvania and Missouri, are split among more than one.
2
Open the supplemental or ancillary page. Blues often file hospital cash plans under supplemental, ancillary or voluntary benefits rather than under health plans.
3
Find the issuer’s name. Read the disclaimer at the bottom of the product page or brochure. It names the company that pays claims.
4
Ask HR about workplace versions. Group plans sold through employers, such as the Texas and Florida designs, may never appear on a public individual shopping page.
5
Request the outline of coverage. That state-filed document lists the daily benefit, day limits, look-back period and exclusions for your state.

If your Blue lists nothing, a hospital plan from another insurer can still sit next to your Blue medical plan. Our explainer on how hospital indemnity insurance works covers the claim process step by step.

Stacking a Cash Plan on Blue Medical Coverage or an HDHP

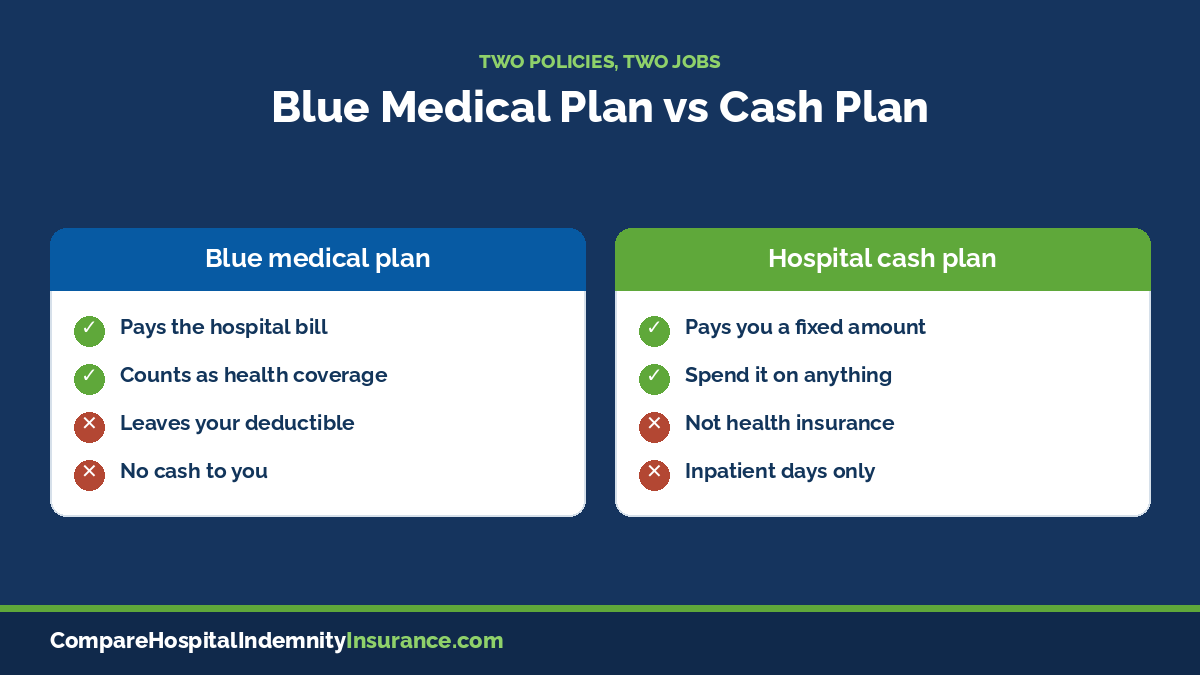
A hospital indemnity policy pays you a set amount for qualifying hospital days, while your Blue medical plan pays the hospital. The two do not coordinate, so the cash arrives on top of what your medical plan pays and you decide how to spend it, whether on a deductible, rent or travel to the hospital.

Example stay Kansas schedule math Example payout
2-day illness admission 2 days x $50 $100
5-day illness admission 3 days x $50 + 2 days x $200 $550
5-day accident admission 5 days x $200 $1,000
5-day stay, days 4 and 5 in ICU 3 days x $50 + 2 ICU days x $400 $950

Examples only, worked from the published Kansas Secure Hospital Indemnity Plan schedule. Your plan’s benefits, day counts and exclusions may differ.

HSA owners:

Federal tax rules treat insurance that pays a fixed amount per day of hospitalization as permitted coverage alongside a health savings account. Plans that add doctor-visit or outpatient benefits can be a different story, which is why some group designs, such as the Guardian plan sold through Independence Blue Cross, are marketed with HSA-compatible options. Ask for written confirmation before you enroll.


Blue Cross Blue Shield hospital indemnity compared with a Blue medical plan: what each one pays during a hospital stay

Hospital Indemnity Quotes

Call a Licensed Agent Now

Your Blue may not sell a hospital plan. A licensed agent can show cash plans available at your address.

☎ 1-888-891-0229

No obligation to enroll

Workplace Blue Coverage or a Policy You Buy Yourself

Most Blue hospital plans in the table are sold either through an employer or directly to individuals, and the two routes trade off differently. Our guide to voluntary hospital indemnity insurance goes deeper on payroll plans.

Through an employer
✔

Group designs like the Independence Blue Cross plan were sold as guaranteed issue
✔

Claims can be matched to your Blue medical claims, as Blue Cross and Blue Shield of Texas describes
✔

Premiums come out of each paycheck
Bought on your own
✕

Some designs ask health questions, such as the LifeSecure plan outside ages 64.5 to 66
✕

You choose the daily amount instead of your employer
✕

The policy stays in force when you change jobs, as long as you pay

Limits That Apply to Every Blue Hospital Plan

Whatever the issuer, these policies share the same basic boundaries. The Kansas and Florida Blue documents both carry the warning that this is a fixed indemnity policy and not health insurance.

Not a health plan
A hospital cash policy is supplemental, limited-benefit coverage. It does not replace health insurance and is not minimum essential coverage under the Affordable Care Act.
Look-back rules
Recent conditions can be excluded for months after the start date, from 6 months on LifeSecure to 365 days on the Kansas plan.
Inpatient only
Benefits are tied to an inpatient admission. Observation stays, rehab facilities and custodial care are commonly excluded.
Medicare is separate
Blue hospital plans built for people on Medicare follow different rules and are outside the scope of this guide.

To weigh a Blue-sold plan against non-Blue carriers on benefits and cost together, use our side-by-side guide to comparing hospital indemnity insurance.

No-cost comparison

Line Up a Blue Plan Against Other Insurers

See admission and daily benefits from several companies before you add a cash plan to your Blue coverage.

Plan availability, eligibility, and benefits vary by state and policy.

BCBS Hospital Indemnity: Common Questions

➤ Does every Blue Cross Blue Shield company offer hospital indemnity insurance?

No. Each of the 33 Blue companies chooses its own supplemental products. Some publish a hospital indemnity plan, some offer one only to employers, and many do not list one at all.

➤ Do I need a Blue medical plan to buy a Blue-sold hospital cash policy?

The pages reviewed for this guide do not require Blue medical coverage. The Kansas plan does require enrollment in some form of minimum essential coverage for guaranteed acceptance, and other issuers set their own eligibility rules.

➤ Who pays the claim on a BCBS hospital indemnity plan?

The issuer named on the policy. For several Blues that is a partner company such as LifeSecure Insurance Company, USAble Life, Dearborn Life Insurance Company or Guardian, not the Blue itself.

➤ Will a hospital indemnity plan lower what my Blue medical plan pays?

No. The two policies pay separately. Your medical plan pays the hospital under its own terms, and the cash plan pays you its fixed amount for each qualifying day.

➤ Is a Blue hospital cash plan enough coverage on its own?

No. It is limited-benefit coverage that pays set amounts, does not replace health insurance and does not count as minimum essential coverage, so it works only alongside a major medical plan.

Blue or Not Blue

Call a Licensed Agent Now

Compare daily benefits, day limits and look-back rules from several insurers in one conversation.

☎ 1-888-891-0229

No obligation to enroll

Russell Noga, licensed insurance agent

About the Author: Russell Noga

Russell Noga is a licensed insurance agent and the founder of ZRN Health & Financial Services, LLC. He has helped people compare health and supplemental insurance for more than 16 years and reviews every page on Compare Hospital Indemnity Insurance before it is published. Learn more about us or read our Editorial Standards.

CompareHospitalIndemnityInsurance.com is operated by ZRN Health & Financial Services, LLC, a Texas limited liability company based in Austin, Texas. We are not connected with or endorsed by any government agency.