Speak with a licensed insurance agent

1-888-891-0229

MetLife Hospital Indemnity Insurance: How the Employer Plan Works, From Enrollment to Claim

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 19, 2026

MetLife hospital indemnity is group insurance you buy through your job that pays you a set cash amount when you are admitted to a hospital, plus a daily amount for each covered day. Your employer chooses the dollar amounts. To weigh it against other hospital indemnity insurance companies, or to compare hospital indemnity insurance you can buy yourself, start below.

Individual coverage

Your Job Doesn't Offer MetLife? See Plans You Can Buy

Enter your ZIP to compare individual hospital indemnity plans.

Plan availability, eligibility, and benefits vary by state and policy.

MetLife in brief

MetLife hospital indemnity is employer-sponsored coverage issued by Metropolitan Life Insurance Company that pays a lump sum per hospital admission and a daily benefit per covered day, directly to you. You enroll at work with no health questions, file claims online or in the MetLife app, and can usually keep the policy after you leave by paying the premium yourself.

Who Issues MetLife Hospital Coverage and Who Can Get It

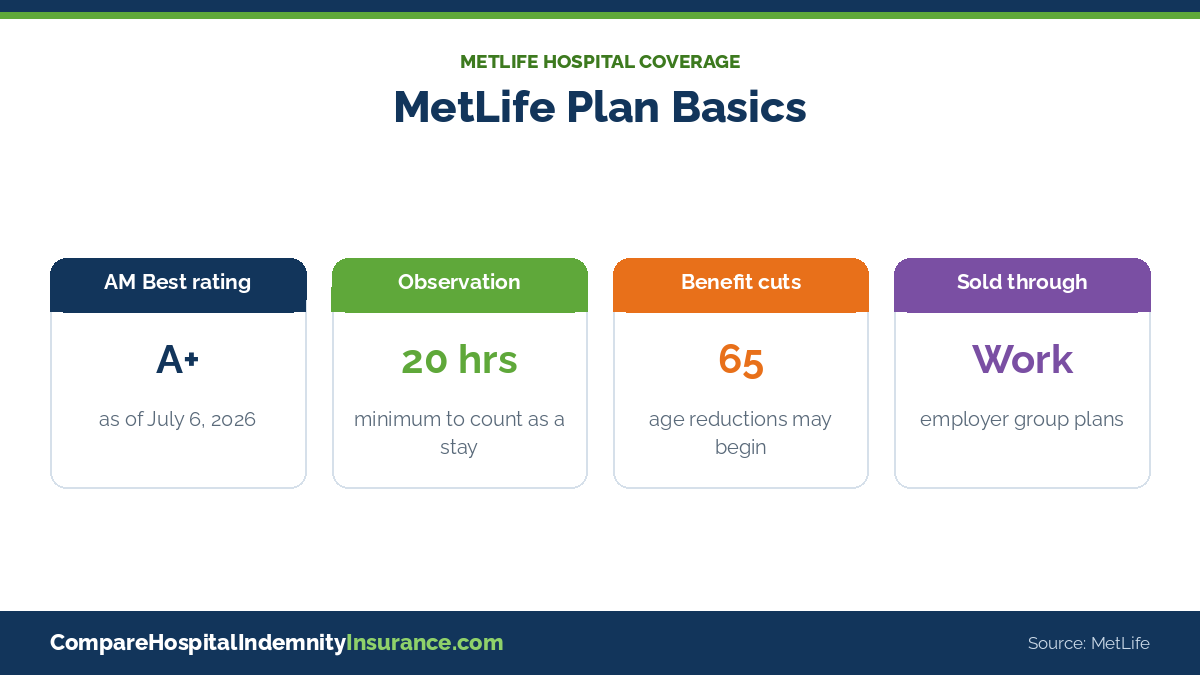
The insurer on every MetLife hospital summary is Metropolitan Life Insurance Company of New York, New York. MetLife’s ratings page shows an A+ financial strength rating from AM Best for that company, as of July 6, 2026. The group policy forms are GPNP12-AX, GPNP13-HI, GPNP16-HI and GPNP12-AX-PASG; benefit guides often call the product HI16.

  • Sold through work. Employers, unions and public agencies buy the group policy. We found no MetLife hospital indemnity plan that a person can buy directly, outside a workplace or group program.
  • No health questions. MetLife guarantees coverage without a medical exam as long as you are actively at work and covered dependents are not under the medical restrictions listed on the enrollment form.
  • State rules apply. Some states require you to have medical coverage before you can enroll, and MetLife notes the plan is still pending approval in certain states.
  • Cash goes to you. MetLife pays you, not the hospital, no matter what your other insurance covers.

This is a limited-benefit fixed indemnity policy. MetLife says it is not health insurance and not a substitute for medical coverage, and fixed indemnity plans do not count as minimum essential coverage under the Affordable Care Act.

MetLife hospital indemnity at a glance: AM Best A+ rating, 20-hour observation rule, age 65 benefit reductions and group-only enrollment

What Three 2026 MetLife Employer Plans Pay for a Short Stay

MetLife has no national price list; each employer sets its own amounts. The table lines up three summaries current for 2026 enrollment, plus our own example math.

Plan line (Low / High) IBM, coverage effective 1/1/2026 Nevada System of Higher Education, 2026-2027 Boeing, 2025 summary
Admission lump sum $1,000 / $2,000, up to 5 a year $500 (1 a year) / $1,000 (4 a year) $1,000 / $2,000, up to 4 a year
Intensive care admission Extra $1,000 / $2,000 $1,000 / $2,000 ICU admission amount Extra $1,000 / $2,000
Daily benefit and cap $100 / $120, 31 days a year $100 / $200, up to 31 days $100 / $200, 30 days a year
First paid day May start on day 2 Low: day 2. High: day of admission Not stated in the summary
Unusual extras Newborn nursery and rehab days Mental health and substance use stays covered without a prior hospital stay Ambulance, doctor visits, outpatient therapy and a $75 screening benefit
Our example: 3 days, Low $1,200 $700 $1,200 to $1,300
Our example: 3 days, High $2,240 $1,600 $2,400 to $2,600
Our example: 5 days, High $2,480 $2,000 $2,800 to $3,000

Sources: MetLife hospital indemnity plan summaries for IBM (coverage effective 1/1/2026, hosted on metlife.com), the Nevada System of Higher Education (2026-2027 plan summary comparison, sickness benefits) and Boeing (hosted on metlife.com, copyright 2025). Example rows are our math, not MetLife figures: one covered person, no ICU, stay length counts the admission day, IBM daily pay assumed to start on day 2. Boeing does not say which day daily pay starts, so a range is shown. Checked Nov. 2026.

Measured against real costs

KFF’s 2025 Employer Health Benefits Survey puts the average deductible for single coverage at $1,886. Only the IBM and Boeing High options beat that on a 3-day example stay, and no Low option comes close. Hospitals spent an average of $3,297 per adjusted inpatient day in 2024 (KFF analysis of American Hospital Association data), so the cash covers your share of a bill, not the bill.

For every line of a schedule, see our MetLife hospital indemnity payout chart page.

What Counts as a Covered Stay, and What Does Not

Most MetLife hospital checks start with one test: were you confined in a hospital? IBM’s plan pages spell it out.

MetLife pays when
  • ✔
    A physician has you assigned to a hospital bed as a resident inpatient, intensive care included
  • ✔
    You stay in a hospital observation area for no less than 20 continuous hours on a physician’s advice
  • ✔
    The building is a hospital, since nursing homes, convalescent care and extended care facilities are left out

An emergency room visit or outpatient treatment on its own does not trigger the admission benefit. Summaries also warn that some benefits need a prior hospital stay and that a pre-existing condition limit may apply to sickness benefits. Our guide to what does MetLife hospital indemnity cover reads two MetLife certificates side by side, exclusions included.

Expecting a baby:

Many MetLife group plans treat a delivery stay as a covered sickness, but waiting periods and pre-existing condition rules can block a birth claim when coverage starts after you are already pregnant. Timing rules and delivery examples are on our MetLife hospital indemnity pregnancy page.

How to Enroll: Open Enrollment, New Hires and Life Events

You sign up through your employer’s benefits system, not with MetLife. IBM, for example, held its annual enrollment from October 26 to November 9, 2026, for MetLife hospital coverage that starts January 1, 2027. Its current summary prices employee-only coverage at $5.71 a month on the Low option and $10.22 on the High option.

1
Find the plan in your enrollment portal. It usually sits with voluntary benefits such as accident coverage.
2
Choose a level and who to cover. Many employers offer Low and High options in four tiers: you alone, you and a spouse, you and your children, or the whole family.
3
Be on the job when coverage begins. MetLife’s group coverage takes effect only if you are actively at work on the scheduled start date.
4
Use a life event for mid-year changes. The University of Pittsburgh’s MetLife FAQ lets members add or remove dependents after a qualifying status change such as marriage, divorce, birth or adoption.

If your employer offers two levels, the choice comes down to the extra paycheck cost against the bigger check. Our MetLife hospital indemnity low vs high guide works through the break-even math.

How to File a MetLife Hospital Indemnity Claim

You file with MetLife yourself, usually after discharge; your medical insurer does not send it for you.

MyBenefits website
Start the claim at mybenefits.metlife.com. The same login shows your certificate of insurance and lets you set up direct deposit.
MetLife mobile app
Employer claim guides list the MetLife app as a second electronic way to submit.
Paper routes
Claim forms carry a fax number and mailing address, and some employer guides add an email option.

Ask the hospital for records that name the patient and show admission and discharge dates, the diagnosis and whether any time was spent in intensive care.

How long it takes:

MetLife’s claim guides say a complete claim generally takes about 10 business days to process, and the money arrives 7 to 10 business days after approval by check or direct deposit. A claim with missing papers takes longer.

Russell Noga, licensed insurance agent

Claim-file tip

A later bill for a hospital stay already reported to MetLife does not need a new claim form. Writing the claim number or certificate number on every page sent links the papers to the open claim.

Russell Noga, Licensed Insurance Agent

Keeping MetLife Coverage After You Leave Your Job

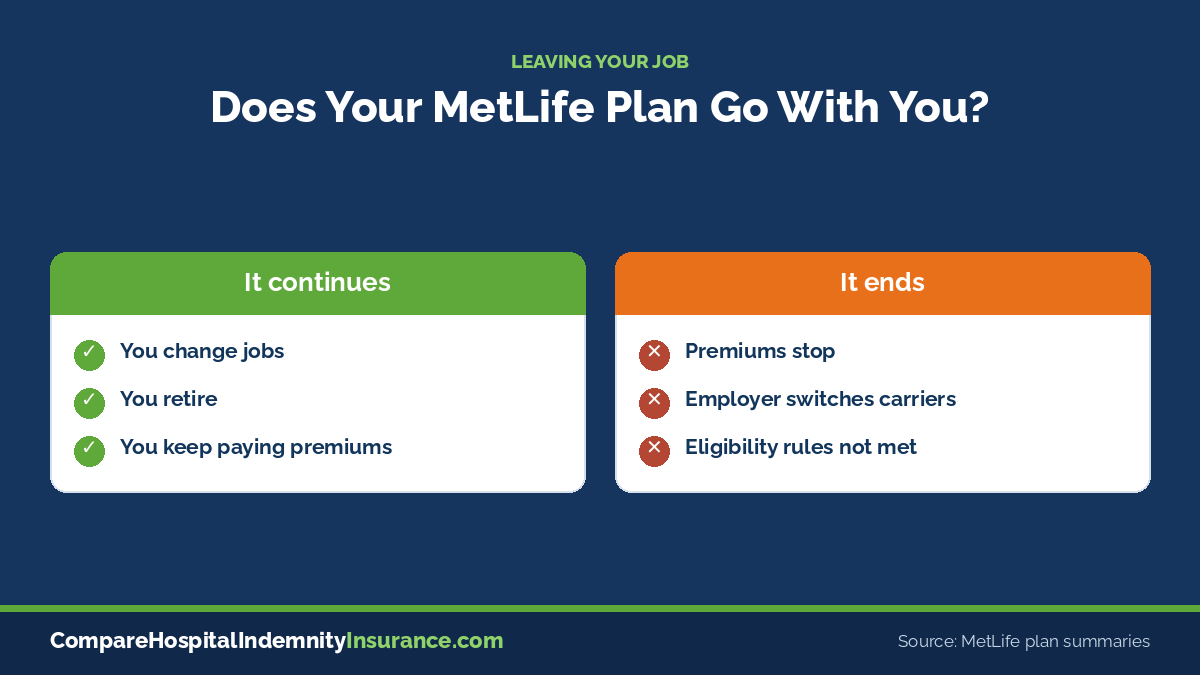
MetLife hospital coverage is portable. If you quit, change jobs or retire, you can keep it by paying premiums yourself under MetLife’s Continuation of Insurance with Premium Payment provision, subject to eligibility rules. Per IBM’s plan page, coverage ends if you stop paying or if the employer offers you similar coverage through another carrier.

Before your last day:

Ask HR or MetLife for the continuation paperwork and any deadline while you can still reach the benefits portal.

All three summaries in our table also say benefits may be reduced beginning at age 65, so retirees who plan to keep the policy should ask MetLife for the reduction schedule. On Medicare, the plan still pays its fixed amounts no matter what Medicare pays.


MetLife hospital indemnity portability: when coverage continues after leaving a job and when it ends

Hospital Indemnity Quotes

Call a Licensed Agent Now

No MetLife plan at work? Licensed agents can quote individual hospital plans in your state.

☎ 1-888-891-0229

No obligation to enroll

Is MetLife Hospital Indemnity Worth It for You?

Reasons it can pay off
✔

Guaranteed coverage at work with no health questions
✔

Low payroll cost, such as IBM’s $5.71 a month for one person on the Low option
✔

Cash paid to you on top of your medical plan
✔

Portable when you leave the job
Reasons to think twice
✕

Low options often pay less than an average deductible for a short stay
✕

No admission payment for an ER-only visit or a short observation stay
✕

Your employer, not you, sets the amounts
✕

Possible age-65 reductions and pre-existing condition limits

A quick test: compare the High option’s example payout for a 3-day stay with your medical plan’s deductible. If it covers most of the deductible and a stay is likely next year, such as a planned surgery, a baby on the way or a chronic condition, the premium tends to earn its keep. If not, the same dollars may do more in emergency savings.

Free quotes

Stack Your MetLife Benefits Against Other Carriers

Check admission and daily amounts sold in your state.

Plan availability, eligibility, and benefits vary by state and policy.

MetLife Hospital Indemnity Insurance: Your Questions Answered

➤ What is MetLife hospital indemnity insurance?

It is a group fixed indemnity policy from Metropolitan Life Insurance Company that employers offer as a voluntary benefit. It pays you set cash amounts for a hospital admission and each covered day, on top of your medical plan.

➤ How much does MetLife hospital indemnity pay?

It depends on the plan your employer bought. In the three current summaries we reviewed, admission benefits ran from $500 to $2,000 and daily benefits from $100 to $200, so our 3-day example stay paid roughly $700 to $2,600. Your own plan summary has the exact amounts.

➤ Does MetLife hospital indemnity cover pregnancy?

Many MetLife plans pay the admission and daily benefits for a delivery stay because childbirth counts as a covered sickness. Waiting periods and pre-existing condition limits can apply if you enroll after becoming pregnant, so read your certificate before the due date.

➤ How do I file a MetLife hospital indemnity claim?

Submit it online through MyBenefits at mybenefits.metlife.com or in the MetLife mobile app, with hospital records showing the patient, the admission and discharge dates, the diagnosis and the room type. Paper forms can also be faxed or mailed.

➤ Can I keep MetLife hospital indemnity after I leave my job?

Usually yes. MetLife lets you continue the coverage by paying premiums directly, subject to eligibility rules. It ends if you stop paying or if your employer offers you similar coverage through another carrier.

➤ Can I buy MetLife hospital indemnity on my own?

We could not find a MetLife hospital indemnity plan sold directly to individuals; MetLife offers it through employers and other groups. Other carriers sell individual plans you can buy without an employer.

➤ Is MetLife hospital indemnity insurance worth it?

It is worth more when a hospital stay is likely and the High option pays close to your deductible.

Compare Before Enrollment

Call a Licensed Agent Now

Line up your MetLife benefits against individual plans from several carriers.

☎ 1-888-891-0229

No obligation to enroll

Russell Noga, licensed insurance agent

About the Author: Russell Noga

Russell Noga is a licensed insurance agent and the founder of ZRN Health & Financial Services, LLC. He has helped people compare health and supplemental insurance for more than 16 years and reviews every page on Compare Hospital Indemnity Insurance before it is published. Learn more about us or read our Editorial Standards.

CompareHospitalIndemnityInsurance.com is operated by ZRN Health & Financial Services, LLC, a Texas limited liability company based in Austin, Texas. We are not connected with or endorsed by any government agency.