Speak with a licensed insurance agent

1-888-891-0229

UNL Hospital Indemnity: Shield Plans, Riders, Waiting Rules and Example Payouts

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 16, 2026

UNL hospital indemnity is a pair of individual limited-benefit policies from United National Life Insurance Company of America, the Hospital Indemnity Shield and the Guaranteed Issue Hospital Indemnity Shield, that pay you a fixed daily cash amount for a hospital stay. UNL’s product pages list both for buyers age 50 to 85, so this is mainly a plan for people in their fifties, sixties and later, not for young families.

Carrier check

Price a UNL Shield Next to Other Hospital Plans

Enter your ZIP to see which carriers file hospital indemnity plans in your state.

Plan availability, eligibility, and benefits vary by state and policy.

The money goes to you, not the hospital, and you choose how to use it. To weigh UNL against insurers that also sell to younger adults, our guide to hospital indemnity insurance companies covers the wider field.

UNL itself labels these policies limited benefit insurance. They are supplemental, they do not replace health insurance and they are not minimum essential coverage under the Affordable Care Act. If you would rather start with prices in your ZIP code, you can compare hospital indemnity insurance from several carriers at once.

UNL in two sentences

UNL sells two hospital indemnity policies for ages 50 to 85: an underwritten Shield with daily benefits UNL lists at $100 to $900, and a Guaranteed Issue Shield at $100 to $450 a day with a 60-day waiting period. Both pay you cash for each covered hospital day, up to the benefit period you pick.

Who United National Life Is

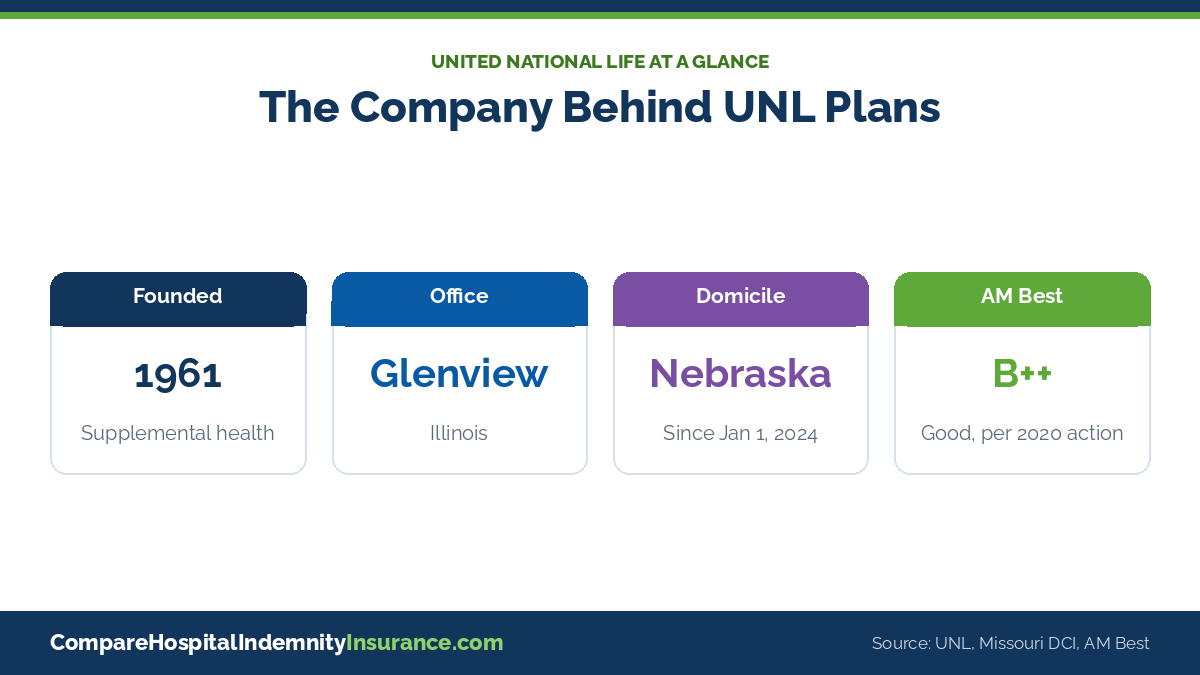
United National Life Insurance Company of America has sold supplemental health coverage since 1961 and calls itself a small, privately held company. Its office is at 1275 Milwaukee Avenue in Glenview, Illinois. Besides hospital indemnity, its current lineup includes Cancer Shield 2.0, Dental Shield 2.0, Home Health Care Shield and a Final Expense Shield life policy.

  • Legal home moved in 2024. Missouri’s insurance department records show UNL redomesticated from Illinois to Nebraska effective January 1, 2024. Its NAIC company code is 92703.
  • A sister company you may know. AM Best has described UNL as an affiliate of Guarantee Trust Life, which is also based in Glenview and sells its own hospital plans.
  • Financial strength. AM Best assigned UNL a B++ (Good) rating in 2017, and its September 2020 action affirmed B++ while raising the issuer credit rating to bbb+. Check AM Best for the current rating before you buy.
  • Complaint record. Missouri’s company page shows zero health complaints against UNL in 2021, 2022 and 2023, on a very small market share.

A B++ rating sits a step below the A-range ratings many larger hospital indemnity carriers hold. It is one more fact to weigh next to price and plan design.

UNL hospital indemnity company snapshot showing founding year, office, legal domicile and AM Best rating

Shield vs Guaranteed Issue Shield: Our Side-by-Side

UNL does not publish one brochure covering both policies, so we built this table from UNL’s product pages, its disclosures page and a 2024 UNL marketing packet filed for a group program. Where those sources differ, both figures are shown.

Feature Hospital Indemnity Shield Guaranteed Issue Shield
Policy form series U1750 (U9910 also listed) U2350
Issue ages 50 to 85 on UNL’s site; 64 to 85 in the 2024 packet 50 to 85 on UNL’s site; 64 to 85 in the 2024 packet
Daily benefit $100 to $900 on UNL’s site; $100 to $750 in the 2024 packet $100 to $450
Benefit days you choose 3 to 10 3 to 12
What starts the benefit Confinement or observation lasting 24 hours, per the packet Confinement or observation lasting 24 hours; observation not in every state
Health questions Yes, standard underwriting None; guaranteed issue
Waiting period None stated in the materials we reviewed 60 days
Pre-existing condition limit None stated in the materials we reviewed 12 months from the effective date
Riders offered Up to eight, varying by state Ambulance and outpatient surgery only
Sample premium in the 2024 packet $13.97 a month $37.27 a month

Sources: unlinsurance.com product and disclosures pages; UNL marketing packet coded UAD21.2-24 and UAD21.3-24. Sample premiums are UNL’s illustrations for one age and plan, not quotes.

Reading the table

The guaranteed issue version costs more for less. In UNL’s own sample, it ran about 2.7 times the monthly premium of the underwritten Shield, with half the top daily amount and a waiting period the Shield does not list.

Riders That Reshape a UNL Policy

The base Shield only pays for hospital days. Most of the flexibility comes from riders, and the 2024 packet gives dollar figures for each one. Some states offer only a few of them; Idaho, for instance, lists just the cancer lump sum and skilled nursing riders.

Ambulance
$50 to $400 per ground or air trip to or from a hospital, once a day, up to four trips a year and 12 in a lifetime. No admission is needed.
Outpatient surgery
$250 to $1,000 per surgery on the Shield, or $100 to $450 on the guaranteed issue version, up to two surgeries a year.
Skilled nursing
$100 to $300 a day after a three-day hospital stay, with a 20-day elimination period and admission within 30 days of discharge.
Cancer and terminal illness
Cancer lump sum options of $1,000, $5,000 or $10,000, with 25% for cancer in situ. Terminal illness pays $100 to $300 a day for up to 100 days.

Outpatient package:

This Shield-only rider bundles a $150 emergency room or urgent care benefit for an accident, $50 a day for outpatient therapy and $150 for an advanced diagnostic exam such as an MRI, each with its own yearly limits.

UNL’s site also notes that in many states the Shield can be sold with an optional $5,000 whole life policy. That is a separate life benefit, so ask for its premium on its own line.

Russell Noga, licensed insurance agent

Underwriting order

The Guaranteed Issue Hospital Indemnity Shield tops out at $450 a day, carries a 60-day waiting period and a 12-month pre-existing condition limitation, and in UNL’s own sample cost more each month than the underwritten Shield. An applicant who can answer the health questions usually gets more benefit per premium dollar by applying for the standard Shield first and using guaranteed issue only after a decline.

Russell Noga, Licensed Insurance Agent

Example Payouts: How the Benefit-Day Choice Plays Out

The number of benefit days you pick matters as much as the daily amount. The examples below use a sample $200 daily benefit and assume the stay is covered, falls outside any waiting period and is the only stay that year. They are our own calculations, not UNL quotes.

Example stay 3 benefit days 5 benefit days 10 benefit days
3 days in the hospital $600 $600 $600
5 days in the hospital $600 $1,000 $1,000
8 days in the hospital $600 $1,000 $1,600
Two 4-day stays in one year $600 $1,000 $1,600

Example figures at a $200 daily benefit. The 2024 packet says benefits restore every calendar year, which suggests the chosen days work as a yearly bank; confirm how your outline of coverage counts them.

What the math shows

  • ✔
    A short stay pays the same no matter how many benefit days you buy, so extra days only help when a stay runs long or you go back in.
  • ✔
    Raising the daily amount lifts every row; adding days lifts only the long-stay rows.
  • ✔
    At the guaranteed issue cap of $450 a day, a 5-day stay with 5 benefit days would pay $2,250 once the waiting period has passed.

Who Can Buy UNL and Where

The age floor is the first filter. Anyone under 50, including working parents and self-employed adults in their thirties or forties, cannot buy either Shield based on UNL’s listed ages. People who are already on Medicare often buy these plans to help with hospital copays, but nothing in UNL’s materials limits them to Medicare enrollees.

1
Check your state. UNL lists hospital indemnity in about 35 states. California, New York and Washington have no listing, and rider choices shrink in states such as Idaho, Virginia and Pennsylvania.
2
Try the underwritten Shield. It asks health questions, but it allows higher daily amounts, more riders and no stated waiting period.
3
Fall back to guaranteed issue if declined. UNL says that version is built for people who do not qualify for a typical hospital indemnity policy.
4
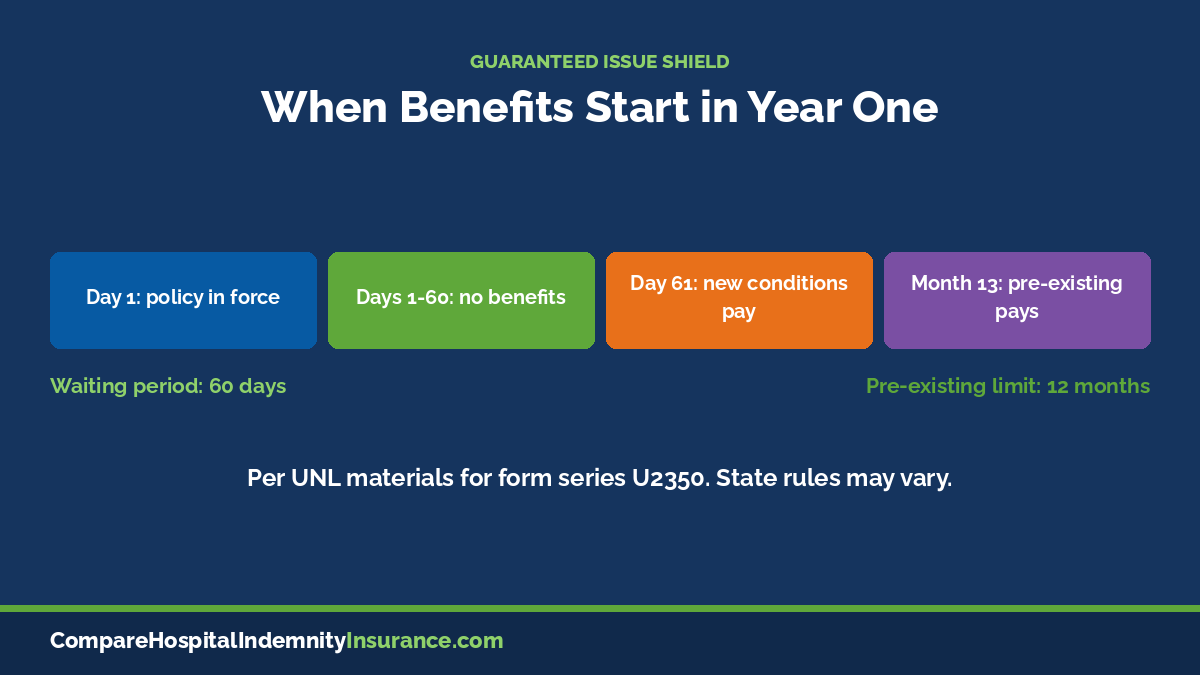
Plan around the first year. On the guaranteed issue policy, nothing pays in the first 60 days, and stays tied to a pre-existing condition are excluded for 12 months.

UNL hospital indemnity guaranteed issue first-year timeline with 60-day waiting period and 12-month pre-existing condition limit

Hospital Indemnity Quotes

Call a Licensed Agent Now

A licensed agent can check whether UNL files its Shield plans in your state and price them next to other carriers.

☎ 1-888-891-0229

No obligation to enroll

How UNL Compares With Larger Carriers

UNL competes with household names on its narrow age band, not on brand. Before deciding, put its numbers next to other plans in our hospital indemnity comparison guide, and read our notes on hospital indemnity insurance reviews to see how complaint data and ratings fit together.

Points for UNL
✔

Daily amounts listed up to $900, higher than many individual plans
✔

A guaranteed issue option for people turned down elsewhere
✔

Stays under observation can count when they last 24 hours
✔

Guaranteed renewable for life while premiums are paid
Points against
✕

Not sold to anyone under 50
✕

B++ rating rather than an A-range rating
✕

Riders and observation coverage vary by state
✕

Premiums can rise for a whole class of policyholders

Because UNL is affiliated with Guarantee Trust Life, you may see both names from the same agent. Our page on GTL hospital indemnity covers the sister company’s plans.

What a UNL Shield Will Not Do

UNL’s disclosures state plainly that these are limited benefit policies with exclusions, limitations and reductions of benefits. The outline of coverage in your state lists them in full, and it is the document to read before you sign.

Keep in mind:

A UNL Shield does not pay your doctor or hospital, does not cover prescriptions and will not satisfy any requirement to carry health insurance. UNL also states that it is not connected with or endorsed by the federal government or the Medicare program.

Guaranteed renewable means UNL cannot cancel the policy because your health changes, but the product pages say UNL may raise premiums on a class basis. Budget for that, especially if you buy near the top of the age range.

Free side-by-side

See Whether UNL or Another Carrier Pays More per Day

Line up daily amounts, benefit days and premiums before you apply.

Plan availability, eligibility, and benefits vary by state and policy.

UNL Hospital Indemnity: Questions Shoppers Raise

➤ What does UNL stand for in insurance?

UNL is short for United National Life Insurance Company of America, a supplemental health insurer founded in 1961 with offices in Glenview, Illinois. It is not connected to the University of Nebraska-Lincoln, which shares the same initials.

➤ Can someone under 50 buy a UNL Shield?

Not based on UNL’s listed issue ages, which start at 50 for both hospital policies. Younger adults, families and self-employed buyers would need a carrier that sells to their age group.

➤ Does the UNL guaranteed issue plan cover pre-existing conditions?

Only after 12 months. The policy has a 12-month pre-existing condition limitation from the effective date, and no benefits are paid in the first 60 days for any stay.

➤ Does UNL pay for an observation stay?

UNL’s materials say benefits start with confinement or observation lasting 24 hours, which many plans do not cover. Observation is not available in every state, so check your outline of coverage.

➤ Who owns United National Life?

UNL describes itself as small and privately held and does not name a parent on its site. AM Best has called it an affiliate of Guarantee Trust Life, another Glenview-based insurer.

➤ Is UNL hospital indemnity worth it for someone on Medicare?

It can help with the daily hospital copays some Medicare Advantage plans charge, but it does not replace Medicare or a Medigap plan. Compare the yearly premium with the copays you would actually face before buying.

Compare Before You Apply

Call a Licensed Agent Now

Get UNL’s daily amounts and premiums side by side with other hospital plans in one call.

☎ 1-888-891-0229

No obligation to enroll

Russell Noga, licensed insurance agent

About the Author: Russell Noga

Russell Noga is a licensed insurance agent and the founder of ZRN Health & Financial Services, LLC. He has helped people compare health and supplemental insurance for more than 16 years and reviews every page on Compare Hospital Indemnity Insurance before it is published. Learn more about us or read our Editorial Standards.

CompareHospitalIndemnityInsurance.com is operated by ZRN Health & Financial Services, LLC, a Texas limited liability company based in Austin, Texas. We are not connected with or endorsed by any government agency.