Speak with a licensed insurance agent

1-888-891-0229

GTL Hospital Indemnity: Advantage Plus Elite Benefits, Ages, States and Ratings

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 7, 2026

GTL hospital indemnity is an individual hospital cash policy from Guarantee Trust Life Insurance Company, sold today mainly as Advantage Plus Elite, that pays you a fixed daily amount when you are confined in a hospital, for the number of days you pick when you buy it. The money goes to you rather than to the hospital unless you assign it to a provider.

Free quotes

Price a GTL Plan Next to Other Hospital Cash Policies

Enter your ZIP to see which hospital indemnity carriers sell in your state.

Plan availability, eligibility, and benefits vary by state and policy.

GTL is a family-run insurer founded in 1936 and based in Glenview, Illinois. Its hospital plan is sold to individuals through licensed agents rather than through employers, which makes it one of the few carriers where a 45-year-old with a high-deductible plan can buy hospital coverage on their own. To see where GTL fits among other carriers, read our guide to hospital indemnity insurance companies.

Like every policy in this category, a GTL plan is a limited-benefit supplement. GTL’s brochures call it a limited benefit policy. It does not replace major medical insurance, and it is not minimum essential coverage under the Affordable Care Act. You can also compare hospital indemnity insurance quotes side by side.

Quick answer

GTL hospital indemnity is Guarantee Trust Life’s Advantage Plus Elite policy, which pays a daily cash benefit you choose for hospital stays of six hours or more, with optional riders for ambulance, cancer, surgery, skilled nursing and dental or vision. It is sold to adults 40 to 85 in most states, but not in New York.

Which GTL Products Count as Hospital Indemnity

Only a few GTL products are true hospital confinement policies, and the name on your brochure depends on your state and when the policy was issued.

Advantage Plus Elite
The current flagship, issued on form series G2150. It pays a daily benefit for hospital confinement and adds emergency room, observation and mental health benefits to the base plan.
Advantage Plus
The earlier version, launched in 2005. GTL still lists it in some states, such as Massachusetts, Idaho and New Jersey.
Indemnity Plus Elite
The Florida version of the Elite plan. GTL lists it separately for that state.
Not hospital indemnity
Recover Cash, Short-Term Home Health Care and the cancer and critical illness plans pay for other events. In Connecticut, GTL lists its Elite product as a dental and vision policy.

GTL’s product page says there are currently no products available in New York. Elsewhere, benefit periods and riders vary by state, and your state brochure controls what you can buy.

How the Elite Base Plan Pays for a Hospital Stay

The Elite base plan is built around one choice: how many days of hospital confinement it will pay for each time a benefit period starts. GTL offers 1, 3, 4, 5, 6, 7, 8, 9, 10 or 15 days, and a 31-day period in some states.

1
Pick a benefit period and daily amount. GTL’s 2025 underwriting guide lists $100 to $990 a day for 3- to 15-day periods, chosen in $10 steps. A 1-day period instead pays a single larger amount of $1,000 to $2,500.
2
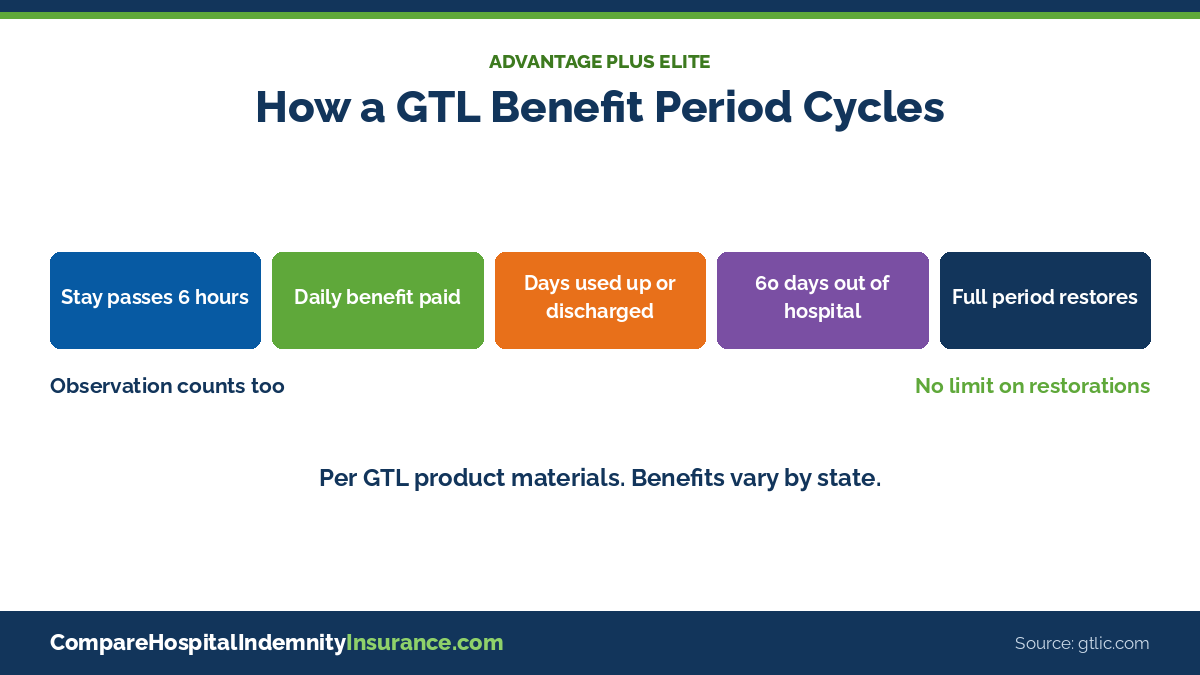
Benefits start at six hours. GTL says the base benefits begin after a six-hour stay, and its product comparison says observation stays pay 100 percent of the daily benefit with no limit.
3
Emergency room and urgent care. The base plan pays $150 for an emergency room or urgent care visit, even when you are not admitted.
4
Mental health confinement. An inpatient stay for a mental or nervous disorder pays $175 a day for up to 7 days in a calendar year, in place of the regular daily benefit.
5
Restoration. After you have been out of the hospital for 60 days in a row, the benefit period restores in full, with no cap on how many times it can restore.

Example payout:

GTL’s own example uses a $300 daily benefit on a 6-day plan, which pays up to $1,800 for one stay. It is an illustration, not a quote.


GTL hospital indemnity benefit cycle from a six-hour stay to full restoration after 60 days out of the hospital

Three GTL Filings Compared: What Changed From Advantage Plus to Elite

No single GTL sheet shows how its hospital plan has changed. This table lines up three of GTL’s own documents: a 2020 Utah Advantage Plus brochure, GTL’s 2023 Elite product comparison and the Elite underwriting guide revised in August 2025.

Feature Advantage Plus (Utah brochure, 2020) Elite (product comparison, 2023) Elite (underwriting guide, Rev. 8/25)
Policy form G0553-UT G2150 series Not listed
Benefit periods 10 or 21 days 1, 3-10, 15 days; 31 in some states 1 or 3-15 days
Daily benefit $100 to $750 $100 to $750; 1-day plan $1,000 to $2,500 $100 to $990; 1-day plan $1,000 to $2,500
Short stays 12 to 24 hours only with a rider Observation paid at 100%, no limit Not addressed
Emergency room $150 only if admitted within 24 hours $150, urgent care included, no admission needed Not addressed
Pre-existing conditions Not covered for the first 6 months Not stated 6-month lookback; none in North Carolina or Maryland
Issue ages Not stated Not stated 40 to 85

Source: GTL brochure 15B491 (Rev. 1/20), GTL Advantage Plus Elite comparison (2023) and GTL Advantage Plus Elite Underwriting Guide (Rev. 8/25). Benefits vary by state.

Key takeaway

The biggest change is at the short end of a stay. The older plan needed a rider to pay for anything under 24 hours and paid the ER benefit only after an admission. Elite pays from six hours and pays the ER benefit on its own. That matters because many short visits are billed as observation, not an inpatient admission.

Russell Noga, licensed insurance agent

Before you buy

GTL caps the daily hospital benefit at $1,000 across all GTL policies one person holds, according to its 2025 underwriting guide. Anyone adding a second GTL hospital plan, or upgrading an older Advantage Plus policy to Elite, should add up the daily amounts first. Replacing an older Advantage Plus policy is allowed, but it goes through underwriting again, and the six-month pre-existing condition period can start over on the new policy.

Russell Noga, Licensed Insurance Agent

Who Can Buy It: Ages, Health Questions and State Differences

Elite is issued from age 40 through 85. Most buyers answer a short set of yes or no health questions. GTL’s comparison lists five questions with look-back periods of 3 and 12 months, and one application can cover two people. Rates are unisex and set by issue age, with one rate table per state rather than by ZIP code.

Guaranteed issue applies only near Medicare age, starting at 64 and a half. GTL’s documents give different cutoffs: the product page shows up to age 80 in most states and up to 70 in several, while the 2025 underwriting guide says up to, but not including, 75. Guaranteed issue is not offered in New Jersey or Utah, and applying for the cancer rider brings back the health questions at any age.

State What is different
New York No GTL products currently available
Florida Sold as Indemnity Plus Elite
New Jersey Advantage Plus with a 31-day period, $40 to $250 a day, no guaranteed issue
Massachusetts Advantage Plus with 10- or 21-day periods, $100 to $500 a day, issue ages 65 to 85
Idaho Advantage Plus issue ages 64 to 85
Pennsylvania, Texas An extra $15 a day base benefit for the rest of a 31-day period
North Carolina, Maryland No pre-existing condition waiting period

Source: GTL hospital indemnity product page and Elite underwriting guide (Rev. 8/25). State rules change; check the brochure for your state.

Riders That Add to a GTL Policy

Anything beyond hospital days, observation, the ER and mental health stays is added as a rider, and each one raises the premium. Amounts below come from GTL’s 2023 Elite comparison and its Utah brochure.

  • Ambulance: $50 to $400 per trip, up to 4 trips a year and 12 in a lifetime, including air ambulance.
  • Lump sum cancer: $2,500 to $20,000, with 25 percent for cancer in situ, $500 for basal or squamous cell skin cancer and an option that pays again for a recurrence.
  • Skilled nursing facility: Option 1 pays for days 1 to 50 and Option 2 for days 21 to 100, each at $100 to $220 a day.
  • Outpatient surgery: $250 to $1,000 per procedure, up to twice a year.
  • Lump sum hospital: an extra $250, $500 or $750 on top of the daily benefit, available on plans with a benefit period of 3 days or more.
  • Also offered in many states: dental and vision, critical accident and a guaranteed purchase option or wellness benefit.

Watch for:

In the Utah brochure, the cancer and critical accident riders carry a 30-day waiting period and the dental and vision rider waits 3 months. Waiting periods vary by state, so confirm them in the outline of coverage before counting on a rider.

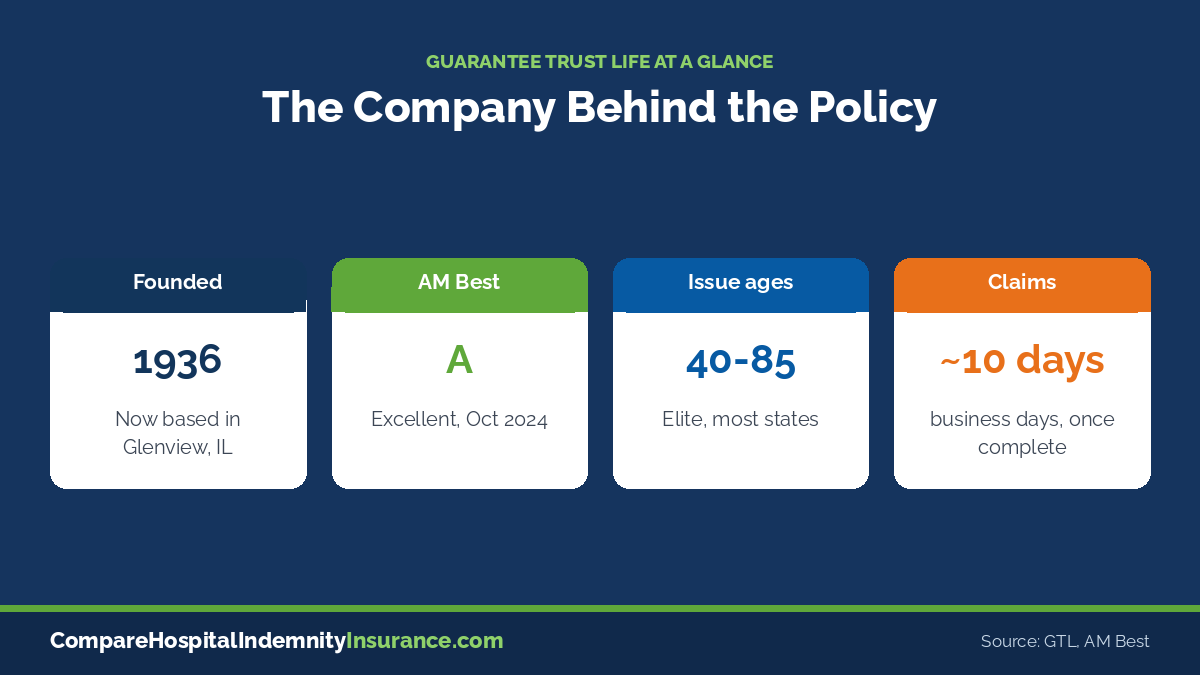
GTL hospital indemnity company profile with founding year, AM Best rating, issue ages and claim processing time

Hospital Indemnity Quotes

Call a Licensed Agent Now

Want GTL’s Elite plan priced for your age and state? A licensed agent can run the numbers with other carriers.

☎ 1-888-891-0229

No obligation to enroll

GTL’s Financial Strength, Premiums and Claims

In October 2024, AM Best raised GTL’s financial strength rating to A (Excellent) from A-, with a stable outlook. AM Best rated its balance sheet strongest and also noted that hospital indemnity makes up more than one-third of GTL’s net premium.

Points in GTL’s favor
✔

Guaranteed renewable for life while premiums are paid
✔

No coordination of benefits with other insurance you carry
✔

GTL says it has not raised rates since the plan began in 2005
✔

Rates are set by issue age and do not rise as you get older
Points to weigh
✕

GTL’s own FAQ says it cannot guarantee fixed premium rates
✕

Minimum annual premium of $240 with any rider and policy fee
✕

Pre-existing conditions are not covered for six months in most states
✕

Sold only through agents; not available in New York

To file a claim, policyholders can use the Claims tab in GTL’s Customer Portal or mail in a claim form with the required documents. GTL says claims are processed in about 10 business days once it has everything it needs. For a refresher on how fixed daily benefits work in general, see how hospital indemnity insurance works, and for typical price ranges across carriers, see our guide to hospital indemnity insurance cost.

Side-by-side

Not Sure GTL Is the Right Fit? Compare a Few Carriers First

See daily benefits, benefit periods and waiting rules from several insurers at once.

Plan availability, eligibility, and benefits vary by state and policy.

GTL Hospital Indemnity: Common Questions

➤ What does GTL stand for in insurance?

GTL is short for Guarantee Trust Life Insurance Company, a Glenview, Illinois insurer founded in 1936. Three generations of the Holson family have run the company.

➤ Can someone under 65 buy GTL hospital indemnity?

Yes. Advantage Plus Elite is issued from age 40, so adults in their 40s and 50s can apply by answering a short set of health questions. People under 40 would need to look at another carrier.

➤ Does GTL pay if I am kept under observation instead of admitted?

Under the Elite plan, GTL’s product comparison says observation stays pay 100 percent of the daily benefit with no limit, and benefits begin after six hours.

➤ Is GTL hospital indemnity sold in every state?

No. GTL says it has no products available in New York, and Florida buyers get a version called Indemnity Plus Elite.

➤ How long does GTL take to pay a hospital indemnity claim?

GTL says it processes claims in about 10 business days once it has all the required documents. Claims can be filed online through the Customer Portal or by mail.

➤ Will my GTL premium go up?

GTL says the plan has not had a rate increase since it began and that rates do not rise as you age, because they are based on your issue age. Its FAQ also says it cannot guarantee fixed premium rates, so a future increase is possible.

➤ Does a GTL plan count as health insurance?

No. It is a limited-benefit fixed indemnity policy that pays set cash amounts. It does not replace major medical coverage and is not minimum essential coverage. Learn more in our guide to fixed indemnity insurance.

Compare Carriers

Call a Licensed Agent Now

See GTL’s daily benefit and riders next to hospital plans from other insurers in your state.

☎ 1-888-891-0229

No obligation to enroll

Russell Noga, licensed insurance agent

About the Author: Russell Noga

Russell Noga is a licensed insurance agent and the founder of ZRN Health & Financial Services, LLC. He has helped people compare health and supplemental insurance for more than 16 years and reviews every page on Compare Hospital Indemnity Insurance before it is published. Learn more about us or read our Editorial Standards.

CompareHospitalIndemnityInsurance.com is operated by ZRN Health & Financial Services, LLC, a Texas limited liability company based in Austin, Texas. We are not connected with or endorsed by any government agency.