Speak with a licensed insurance agent

1-888-891-0229

Aetna Hospital Indemnity Insurance: How the Workplace Plan Pays, Compared Across Three Employers

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 5, 2026

Aetna hospital indemnity insurance is a supplemental plan, usually offered by employers as a voluntary benefit, that pays you a fixed cash amount when you are admitted to the hospital, plus a set amount for each day you stay. Your employer picks the benefit levels, you pay the premium through payroll, and Aetna Life Insurance Company sends the money to you rather than to the hospital.

Free quotes

No Aetna Plan at Work? Compare Your Options

Enter your ZIP to see hospital indemnity plans you can buy on your own.

Plan availability, eligibility, and benefits vary by state and policy.

This guide covers what the plan pays, how it differs by employer, and how a claim gets paid. To see how Aetna fits among other insurers, start with our list of hospital indemnity insurance companies. If your job does not offer it, you can compare hospital indemnity insurance plans sold to individuals and families.

Keep one limit in mind from the start. This is a limited-benefit, fixed indemnity policy. Aetna’s own plan summaries call it a supplement to health insurance, not a substitute for major medical coverage, and it does not count as minimum essential coverage under the Affordable Care Act.

Key point

Aetna hospital indemnity is a workplace cash benefit plan that pays a lump sum when you are admitted and a daily amount while you stay, on top of whatever your health plan pays. The dollar amounts are set by each employer, so the plan summary from your own enrollment kit is the only reliable source for what you would receive.

What the Aetna Plan Is and Who Runs It

Aetna is part of the CVS Health family, as Aetna’s supplemental plans page states, and it says it has offered group supplemental coverage for more than 30 years. The hospital plan can be sold alone or alongside any medical plan, even one from another insurer.

The insurer
Employer plan summaries name Aetna Life Insurance Company of Hartford, Connecticut, as the company that issues the group policy.
The employer
Your company chooses the plan design: benefit amounts, day limits, and whether a low and high option are offered.
You
You choose whether to enroll and whom to cover, pay through payroll deduction, and receive the cash after a covered stay.

Members manage coverage through the myaetnasupplemental.com portal or app. If you want the bigger picture on payroll-deduction coverage from any carrier, our guide to voluntary hospital indemnity insurance covers the general rules.

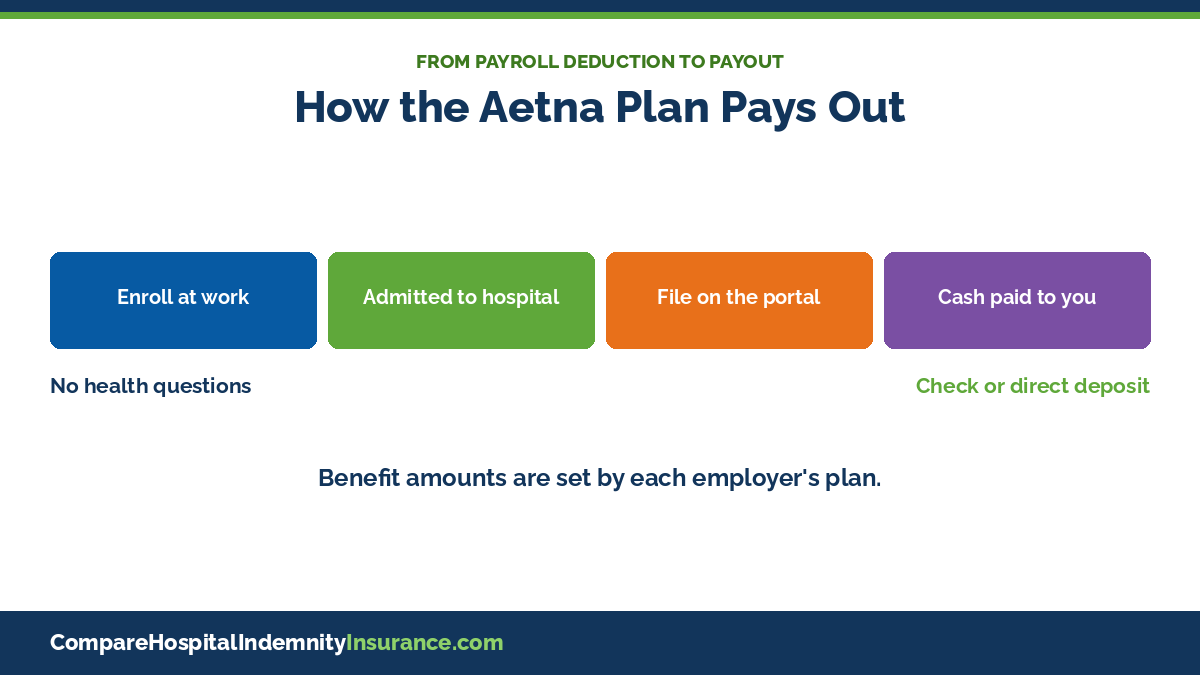
Aetna hospital indemnity timeline from workplace enrollment to hospital admission, online claim and cash payment

Three Aetna Plan Summaries Compared

We lined up three Aetna hospital indemnity summaries to show how much the same product changes from one workplace to the next.

Plan term Bates College (2026 summary) Baylor Scott & White (2025, Low / High) Memorial Healthcare System
Admission lump sum $1,000, 1 stay per plan year $500 / $1,000, each stay separated by 30 days $1,000, 1 stay per plan year
Daily benefit (non-ICU) $100 a day from day 2 $150 / $200 a day from day 1 $200 a day from day 2
ICU $200 a day from day 2 $1,000 / $2,000 ICU admission, then $300 / $400 a day $400 a day from day 2
Day limit 365 days a plan year 365 days a plan year 30 days a plan year
Observation unit Paid at the inpatient level, inside the admission benefit $200 lump sum, once a year; over 24 hours pays as an admission $100 lump sum, once a year
Newborn $100 routine care after an inpatient birth $500 / $1,000 newborn admission plus $150 / $200 a day $100 routine care after an inpatient birth
Waiting period / pre-existing rule None stated in the summary None stated; acceptance guaranteed if eligible None stated in the summary
Extras Waiver of premium after 30 days in a row in the hospital Optional facility rider raises benefits at designated hospitals $50 health screening benefit once a year; waiver of premium

Sources: Bates College Hospital Indemnity Plan summary (2026); Baylor Scott & White Health 2025 Hospital Indemnity Benefit Summary; Memorial Healthcare System HIP benefit summary. All issued by Aetna Life Insurance Company. Checked Nov 2026. Your employer’s certificate controls.

Reading the table

The headline admission amount can match while the real payout does not. A five-day stay with no ICU would pay $1,400 under the Bates design and $1,800 under the Memorial design, because Memorial pays twice as much per day.

Those two figures are worked examples from the summaries above, not a quote. For general math on stays of different lengths, see how much hospital indemnity pays.

Childbirth, Newborn Stays and Observation Status

Pregnancy is one of the main reasons working-age employees pick this plan. An Aetna enrollment FAQ hosted on aetna.com says the plan pays the admission and daily stay benefits when you are hospitalized for a pregnancy, and an Aetna member story describes a family coverage example paying a $1,000 admission benefit plus $100 a day for a three-day delivery stay, or $1,300 in total.

Where the baby fits in

Newborn handling is the line that varies most. Two of the summaries we reviewed pay only a small routine care benefit for a healthy baby, and both say it will not pay for an outpatient birth. The Baylor Scott & White design instead treats the newborn’s own stay like a full admission with its own daily benefit, and it pays stays caused by pregnancy complications the same as any illness. Our page on whether hospital indemnity covers childbirth explains timing rules across carriers.

Observation stays:

Hospitals sometimes keep patients under observation, which is billed as outpatient care. One Aetna design folds observation into the admission benefit, another pays a flat $200 and switches to admission benefits after 24 hours, and a third pays $100 once a year. Ask the hospital for your status in writing.

Enrolling and What Gets Excluded

Because this is a group plan, you sign up during your employer’s open enrollment, when you are first hired, or after a qualifying life event such as a birth or marriage. Aetna’s enrollment FAQ says no health questions are asked, though you must be actively at work when coverage would start, and your benefits begin on the date your employer sets.

Before you elect coverage
  • ✔
    Find the admission line and see whether it pays once a year or for every stay
  • ✔
    Check whether daily benefits start on day 1 or day 2
  • ✔
    Note the yearly day cap, since 30 days and 365 days are both in use
  • ✔
    See whether your summary lists a low and high option and price both
  • ✔
    Look up how newborns are covered if a baby is likely during the plan year

Premiums also vary by employer and by who you cover. As one data point, an older Carilion Clinic flyer listed rates starting at $11.99 a month for employee-only coverage, but that figure applies to that employer’s design only.

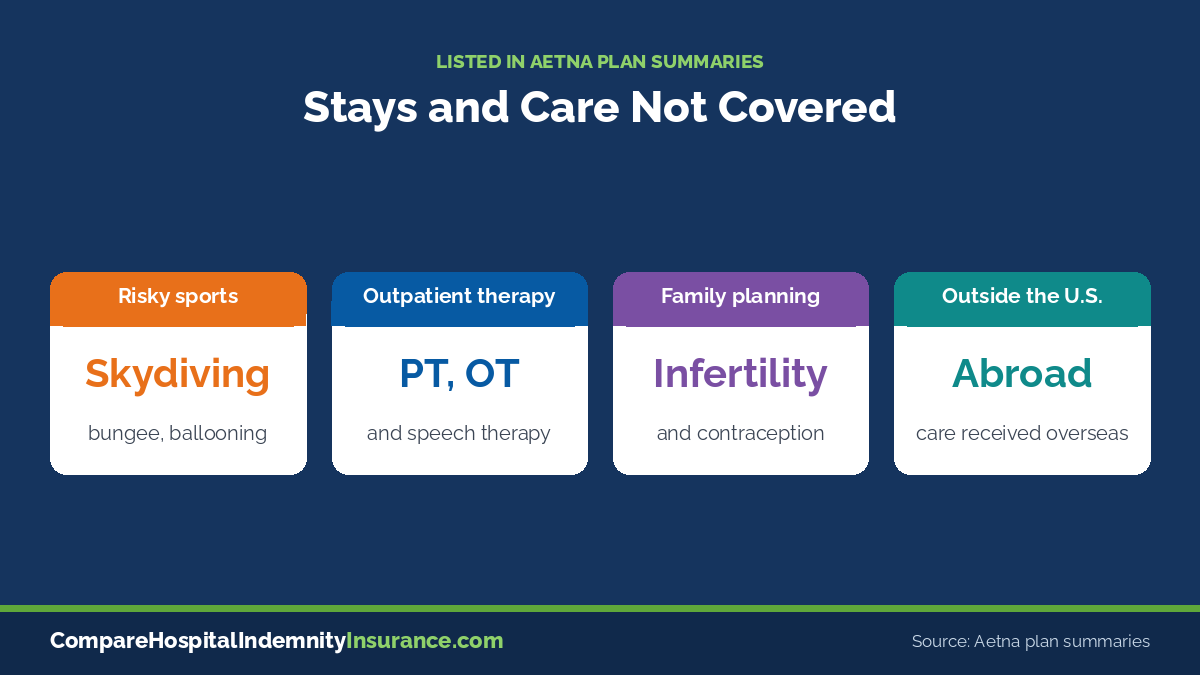
Each summary also excludes stays tied to war, felonies, cosmetic surgery, custodial care and intoxication, with state exceptions.

Russell Noga, licensed insurance agent

Read the plan summary

Aetna summaries differ on how often the admission benefit pays. Bates College and Memorial Healthcare System cap the admission lump sum at one stay per plan year, while Baylor Scott & White pays it for each stay separated by 30 days in a row. The maximum printed next to the admission line shows whether a second hospital stay in the same year would bring another lump sum or only daily benefits.

Russell Noga, Licensed Insurance Agent

How an Aetna Hospital Indemnity Claim Gets Paid

Claims run through Aetna Voluntary Plans, not through your medical insurer, even if Aetna also provides your health plan.

1
Register on the portal. Sign up at myaetnasupplemental.com or in the My Aetna Supplemental app using your member ID or Social Security number.
2
Start a new claim. Choose Report New Claim, answer the questions about the stay, and review your answers.
3
Send proof of the stay. Upload an itemized hospital bill or the UB-04 billing form, or take a photo of it in the app.
4
Choose how to get paid. Benefits go to you by check or direct deposit, which you can set up in the portal.

Members who also have Aetna medical coverage may not need to upload anything. Aetna’s supplemental page describes an easy file tool that uses medical claim data and says a claim can be submitted in about 90 seconds,. Paper claim forms can still be mailed to Aetna Voluntary Plans in Lexington, Kentucky. You can file as soon as the covered event happens, but processing waits until the hospital bill arrives.


Aetna hospital indemnity common exclusions for risky sports, outpatient therapy, family planning and care outside the U.S.

Hospital Indemnity Quotes

Call a Licensed Agent Now

A licensed agent can show individual hospital indemnity plans to fill the gap if your employer does not offer Aetna’s.

☎ 1-888-891-0229

No obligation to enroll

Leaving Your Job, HSAs and Aetna’s Individual Policies

Three rules sit in the fine print of most employer flyers.

  • Portability. All three summaries let you keep coverage for yourself and covered dependents if your job ends, paying Aetna directly. The Baylor Scott & White outline says you must return an election form and the first premium within 30 days after coverage ends, and once ported coverage stops it cannot restart. An older Aetna FAQ said portability was not available in New York or Vermont.
  • Health savings accounts. Each summary states you can enroll even if you have an HSA, because the plan pays fixed cash rather than paying medical bills.
  • Long stays. Two summaries waive premiums after more than 30 days in a row in the hospital, for up to six months, if you stay employed.
Where the workplace plan helps
✔

No health questions at enrollment
✔

Cash paid to you on top of any health plan
✔

Pregnancy stays pay like other admissions
✔

Coverage can follow you after you leave the job
Where it falls short
✕

Benefit levels are fixed by your employer
✕

Some designs pay the admission benefit only once a year
✕

Outpatient care and therapy are generally excluded
✕

Only open to employees of companies that offer it

Aetna also has an individual line. Its Protection Series Hospital Indemnity Flex policy is issued by Continental Life Insurance Company of Brentwood, Tennessee, an Aetna company, and a Texas brochure lists issue ages of 18 to 89. It is marketed mostly to older adults and is separate from the employer plan.

Side-by-side comparison

Check Hospital Cash Plans Sold in Your State

Line up admission and daily benefits from several carriers before you decide.

Plan availability, eligibility, and benefits vary by state and policy.

Aetna Hospital Indemnity Questions We Hear Most

➤ Is Aetna hospital indemnity the same as Aetna health insurance?

No. It is a separate fixed indemnity policy that pays set cash amounts for hospital stays. It does not pay your doctors or hospital, does not meet the Affordable Care Act’s minimum essential coverage rule, and works alongside a medical plan from any insurer.

➤ Does the Aetna plan pay if I have a baby?

Aetna’s enrollment FAQ says a pregnancy hospitalization pays the admission and daily benefits. What the baby receives depends on your employer’s design, ranging from a $100 routine care benefit to a full newborn admission benefit in the summaries we reviewed.

➤ Can I use the plan with a health savings account?

Yes. The Aetna plan summaries we read state that members with an HSA can enroll, since the plan pays a fixed benefit instead of covering medical expenses.

➤ How do I find my Aetna hospital indemnity benefit amounts?

Look for the benefit summary or enrollment kit from your employer’s benefits site, or log in to myaetnasupplemental.com after you enroll. Amounts vary by employer, so a summary from another company will not match yours.

➤ What documents does Aetna need for a hospital claim?

Aetna’s claims flyer asks for an itemized hospital bill or a UB-04 billing form. Members with Aetna medical coverage may be able to skip the upload because the easy file tool pulls the medical claim data.

Compare Before You Enroll

Call a Licensed Agent Now

See how an individual plan’s admission and daily benefits stack up against your workplace option.

☎ 1-888-891-0229

No obligation to enroll

Russell Noga, licensed insurance agent

About the Author: Russell Noga

Russell Noga is a licensed insurance agent and the founder of ZRN Health & Financial Services, LLC. He has helped people compare health and supplemental insurance for more than 16 years and reviews every page on Compare Hospital Indemnity Insurance before it is published. Learn more about us or read our Editorial Standards.

CompareHospitalIndemnityInsurance.com is operated by ZRN Health & Financial Services, LLC, a Texas limited liability company based in Austin, Texas. We are not connected with or endorsed by any government agency.