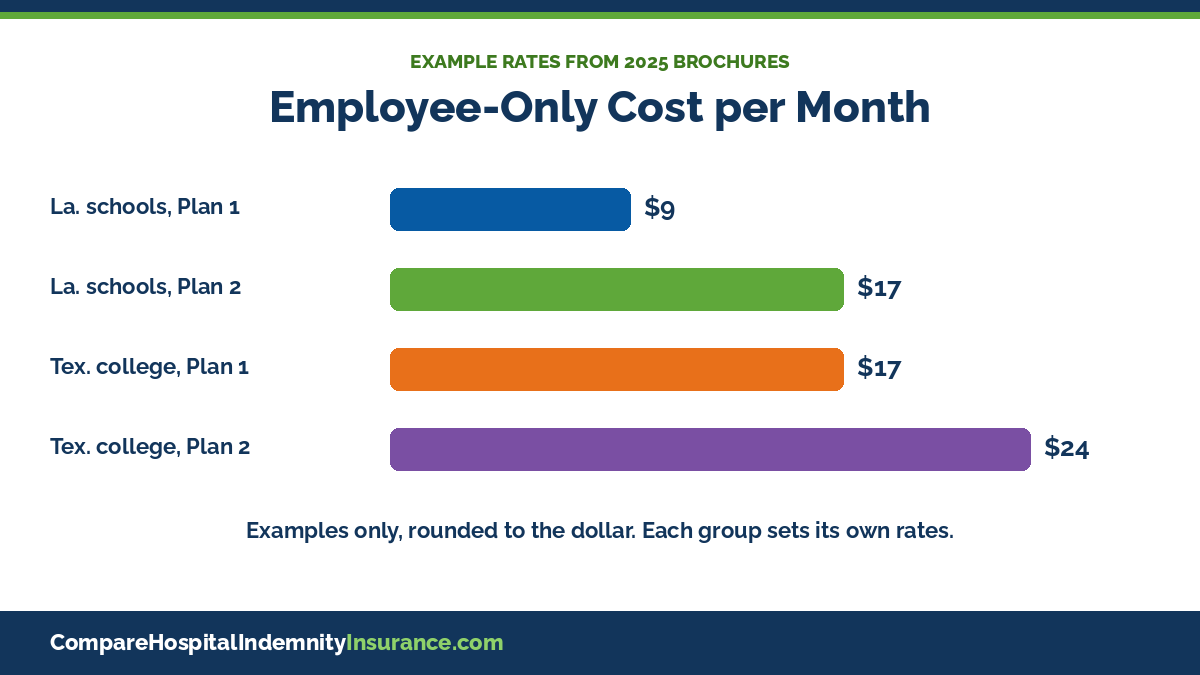
That split matters when you read your paperwork, file a claim or shop. This guide sorts out who issues each version, what three real 2025 employer brochures pay, and where the plan fits among other hospital indemnity insurance companies. With no employer plan open to you, you can compare hospital indemnity insurance sold directly to adults and families.
One rule applies to every version covered here. These are supplemental, limited-benefit policies. The employer brochures state plainly that the coverage is not comprehensive health insurance and does not meet the minimum essential coverage requirement of the Affordable Care Act, so it works only alongside a real medical plan.
Straight answer
Allstate hospital indemnity is supplemental cash coverage for hospital stays, issued at work by American Heritage Life Insurance Company, which The Standard bought from Allstate in 2025. Benefit amounts are set by each employer group, so your own brochure or certificate decides what you would be paid.
Who Sells Allstate Hospital Indemnity in 2026
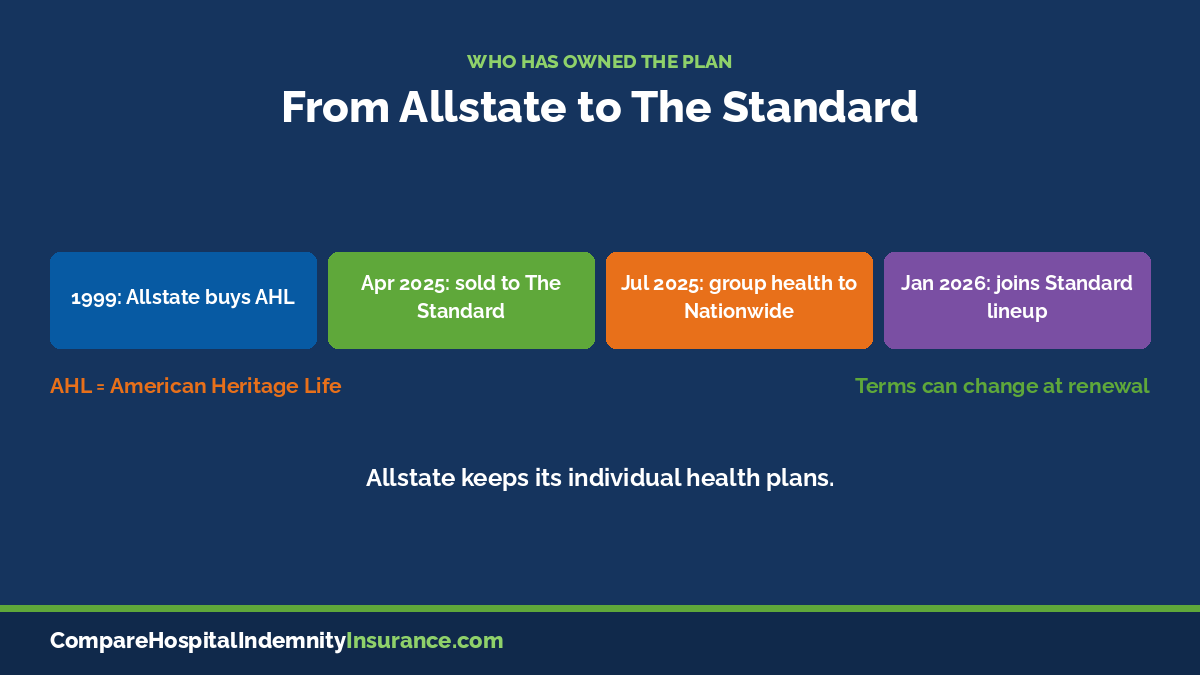
For years the Allstate name covered three different health-related businesses. In 2025 Allstate sold two of them and kept the third, so the company behind your plan depends on how you bought it.
Workplace plans
The Employer Voluntary Benefits unit, marketed as Allstate Benefits and issued by American Heritage Life Insurance Company of Jacksonville, Florida, was sold to StanCorp Financial Group, the parent of The Standard, for about $2 billion. Allstate announced the closing on April 1, 2025.
Employer medical
The Group Health business, which served self-funded employer medical plans, went to Nationwide for $1.25 billion on July 1, 2025. It was not hospital cash insurance.
Individual plans
Allstate kept its individual health business, and its 2025 annual report still lists the Allstate Health Solutions brand.
The Standard says that starting January 1, 2026, it folded the American Heritage voluntary suite, formerly Allstate Benefits, into its own workplace lineup, hospital indemnity included. Employer HR pages from late 2025 tell workers to expect The Standard name on websites and emails while older forms stay in use for a while.
Three 2025 Allstate Benefits Brochures, Compared
Because each employer chooses its own plan design, the same group policy can pay very different amounts. The table lines up three hospital indemnity brochures from 2025 open enrollment, all issued by American Heritage Life on group form GVSP2 or its state version.
| Benefit |
Benefits broker brochure (Jan. 2025) |
Louisiana school district (Plan 1 / Plan 2) |
Texas college (Plan 1 / Plan 2) |
| First day hospital confinement |
$1,500 |
$1,000 / $2,000 |
$1,000 / $1,500 |
| How often the first day benefit pays |
Once per continuous stay, no limit on stays |
Once a month |
Once a month |
| Daily hospital confinement |
$200 a day, up to 30 days |
$100 / $200 a day, up to 10 days |
$100 / $150 a day, up to 10 days |
| Intensive care, per day |
$200, up to 30 days |
$100 / $200, up to 10 days |
$100 / $150, up to 10 days |
| Fixed wellness benefit |
Not listed |
$50 once a year per person |
$50 |
| Pre-existing condition limit |
None, guaranteed issue |
None, guaranteed issue |
Not readable in the posted copy |
| Pregnancy waiting period |
None |
None |
Not readable in the posted copy |
| Issue ages |
18 and over, actively at work |
18 and over, actively at work |
18 and over, actively at work |
Our comparison of three employer-posted Allstate Benefits hospital indemnity brochures for 2025 (a national benefits broker, a Louisiana public school system and a Texas public college). Amounts are examples from those groups only. Your employer’s certificate controls.
What the table shows
The biggest swing is the day cap, not the admission amount. On a long stay, a 30-day cap pays three times as many daily benefits as a 10-day cap.
Name-change note
Brochures printed in early 2025 still describe American Heritage Life as a subsidiary of The Allstate Corporation. That line is out of date, but the coverage is not. The certificate and the issuing company stay the same after the sale, so keep the original certificate on file and use it for any claim, even if new forms show The Standard name.
Russell Noga, Licensed Insurance Agent