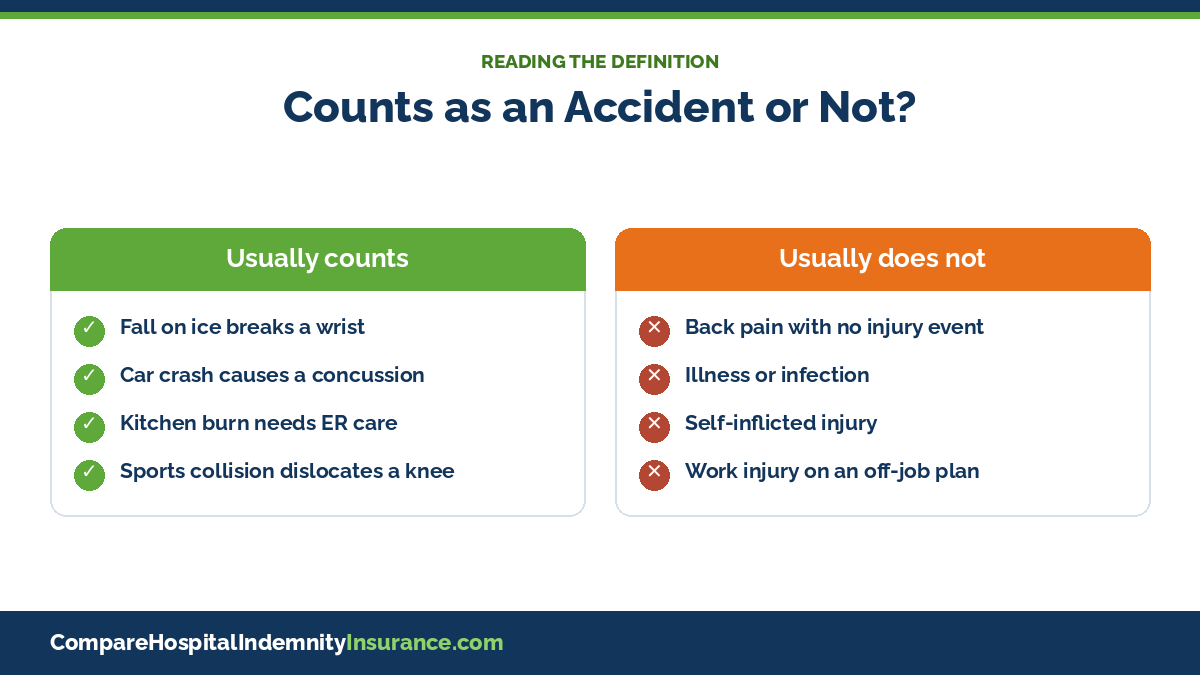
Reading a Schedule of Benefits
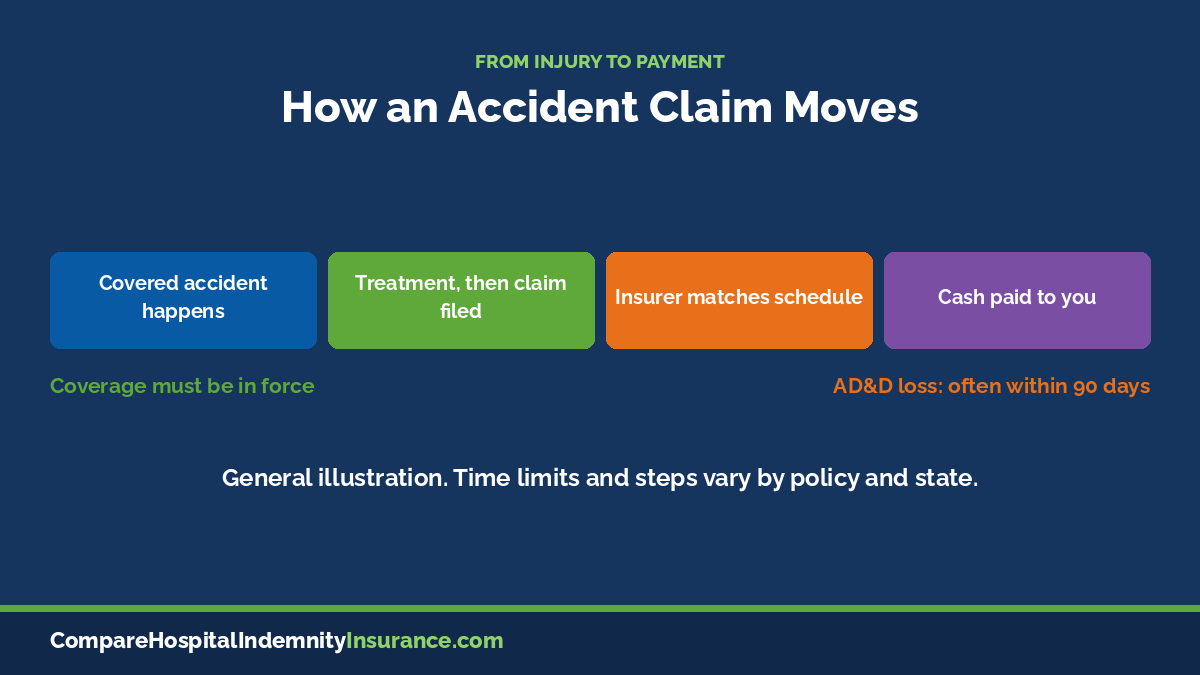
Once an injury qualifies, the schedule decides the money. It is a list of covered events with a dollar figure beside each one, and the insurer pays the listed figure no matter what the provider charged. A single accident can trigger several lines at once.
1
Getting care. Lines for ambulance rides, emergency room or urgent care treatment, and initial doctor visits. These pay on the most claims because nearly every injury starts here.
2
Naming the injury. Lines for fractures, dislocations, burns, cuts, concussions and eye injuries, often split by bone or joint and by whether surgery was needed.
3
Treating and recovering. Lines for imaging, surgery, hospital admission, physical therapy, follow-up visits and medical appliances such as crutches.
4
Catastrophic loss. Lump sums for accidental death, dismemberment, loss of sight or paralysis, usually the largest numbers on the page.
Two plans with similar names can schedule the same injury very differently. A fracture line, for instance, may run from under $100 for a finger to several thousand dollars for a hip on the same policy. How much a given claim adds up to will be the subject of its own guide; here the point is that the schedule, not your bill, sets the payment.
On the Job, Off the Job and Workers’ Compensation
Accident contracts come in two versions when it comes to where you were hurt. The difference is printed on the plan summary and is easy to miss during enrollment.
24-hour (on and off the job)
Pays for covered injuries anywhere, including at work. The workplace claim is paid in addition to any workers’ compensation benefits.
Off-job only (non-occupational)
Excludes injuries that happen while working for pay. Premiums can be lower because workers’ compensation is expected to handle job injuries.
The NAIC model regulation expressly allows insurers to exclude injuries paid under workers’ compensation, employers liability or occupational disease law, which is how off-job plans are built. If you work a physical job, or you are self-employed and not covered by workers’ compensation, the 24-hour version is the one that pays for a workplace injury.
Where injuries actually happen
National Safety Council estimates for 2022 put 86% of medically consulted injuries among workers off the job, a ratio of about 6.3 off-the-job injuries for every one at work. An off-job plan still faces most of the risk.
Three Real Plans, Read Line by Line
Plan brochures rarely put contract terms next to each other, so we pulled them from three documents insurers or employers published for enrollment. Only items printed in each document are shown. Benefits, ages and availability vary by state, employer and plan level.
| Plan reviewed |
Work injuries |
Ages / eligibility |
Wellness or screening |
Portable? |
Example scheduled amounts |
| Aflac Accident Indemnity Advantage, Plan 2 (series A35000) |
24-hour, on or off the job |
Not listed; children must be under 26 at application |
$60 once per 12 months, after 12 months in force |
Not addressed in brochure |
ER $160; ground ambulance $200; fractures $163 to $3,250 |
| MetLife Group Accident, Nevada PEBP plan (Low / High) |
24 hours a day, on or off the job |
Must be actively at work; ages not listed |
$50 once per calendar year |
Yes, while you pay premiums |
Ground ambulance $300 / $600; fractures $100 to $8,000 (Low) |
| Colonial Life Accident 1.0 (form PS01506) |
Employer picks On/Off-Job or Off-Job Only |
Employee and spouse 17 to 64; children 0 to 25 |
$50 per person per year, 30-day wait, on selected plans |
Yes, if you change jobs |
ER $75 to $125; ground ambulance $120 to $200; fractures $90 to $6,000 |
Source: Aflac brochure A35275NRVCOR1; MetLife plan summary for Nevada PEBP, plan year 2026 (Metropolitan Life Insurance Company); Colonial Life Accident 1.0 plan summary, form PS01506. Checked November 2026. The certificate and your state’s version control.
Three things stand out. Only Colonial Life’s form lets the employer choose an off-job design, so the same brand name can mean different coverage at two employers. Wellness benefits are small, $50 to $60 a year, and one has a full-year wait. Portability is spelled out for MetLife and Colonial Life, while the Aflac brochure is silent, so ask before you leave a job.
Worth knowing
Plan summaries mark the work-injury design with short labels such as On/Off-Job, 24-Hour or Off-Job Only. On an off-job plan, an injury that happens while working for pay is excluded, so the accident policy pays nothing for it even when workers’ compensation covers only part of the loss.
Russell Noga, Licensed Insurance Agent
Types of Accident Coverage You Will Run Into
Accident insurance is a family of products, not one contract. The name on the enrollment form tells you how it pays.
- Group or voluntary accident through work. The employer chooses the insurer and plan design, and you usually pay through payroll. Often guaranteed issue during enrollment.
- Individual accident policy. Bought on your own from an insurer or agent. You own the contract, so it does not depend on an employer.
- Accidental death and dismemberment (AD&D). Pays only for death or specific losses such as a limb or eyesight. It can be a standalone policy or a built-in benefit or rider on an accident plan. It does not pay for an ER visit or a broken arm.
- Accident medical expense. Reimburses actual medical bills from an accident up to a maximum, instead of paying a fixed schedule. Some versions pay only after other insurance.
- Student accident. Offered through schools and colleges, often for sports. Many school plans act as secondary coverage that pays leftover bills after the family’s health plan.
Accident Insurance Quotes
Call a Licensed Agent Now
A licensed agent can show whether plans in your state are 24-hour or off-job only.
☎ 1-888-891-0229
No obligation to enroll
Where Accident Insurance Sits Under Federal and State Law
Federal rules treat accident coverage differently from most other supplemental plans. Under 45 CFR 148.220, coverage only for accident, including accidental death and dismemberment, is an excepted benefit in all circumstances. Hospital indemnity and other fixed indemnity plans are excepted only when they meet extra conditions, a topic covered in a separate guide on fixed indemnity insurance.
What that status means for you
Excepted
accident-only coverage is outside the ACA’s major medical rules
Not MEC
it does not count as minimum essential coverage
90 days
the NAIC model window for an AD&D loss to follow the accident
Because the federal health insurance rules do not apply, state insurance departments set the standards: required definitions, minimum AD&D amounts, allowed exclusions and the outline of coverage you receive. That is why the same carrier’s plan can read slightly differently from one state to the next, and why the certificate filed in your state is the document that controls a claim.