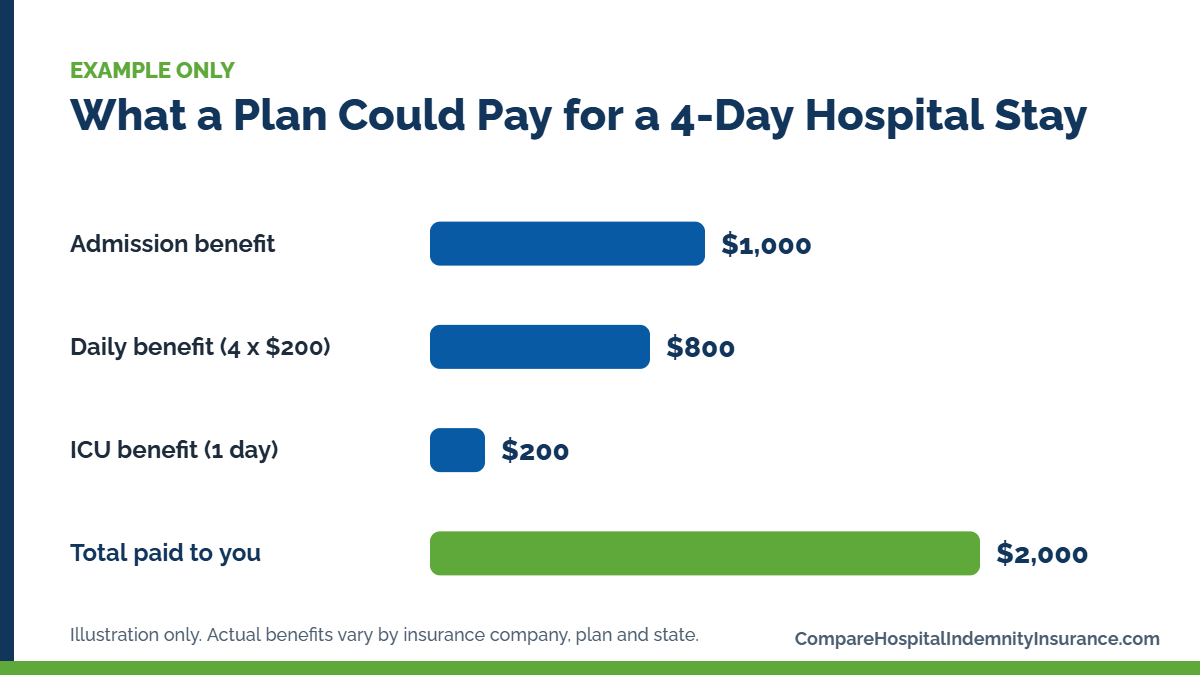
If their employer plan carried a $2,500 deductible, the $2,000 from the hospital indemnity plan covered most of it. That gap between what your health insurance pays and what you still owe is exactly what these policies are built for.
Hospital Indemnity Quotes
Call a Licensed Agent Now
Our licensed agents compare plans from several insurance companies at no cost.
☎ 1-888-891-0229
No obligation to enroll
Hospital Indemnity vs. Health Insurance
|
Health insurance |
Hospital indemnity insurance |
| Who gets paid |
Doctors and hospitals |
You |
| How much it pays |
A share of the actual bill |
A fixed amount set in the policy |
| What it covers |
Most medical care |
Covered hospital stays and listed benefits |
| Counts as minimum essential coverage |
Yes, for qualifying plans |
No |
| Main purpose |
Pay for your care |
Cover out-of-pocket costs and lost income |
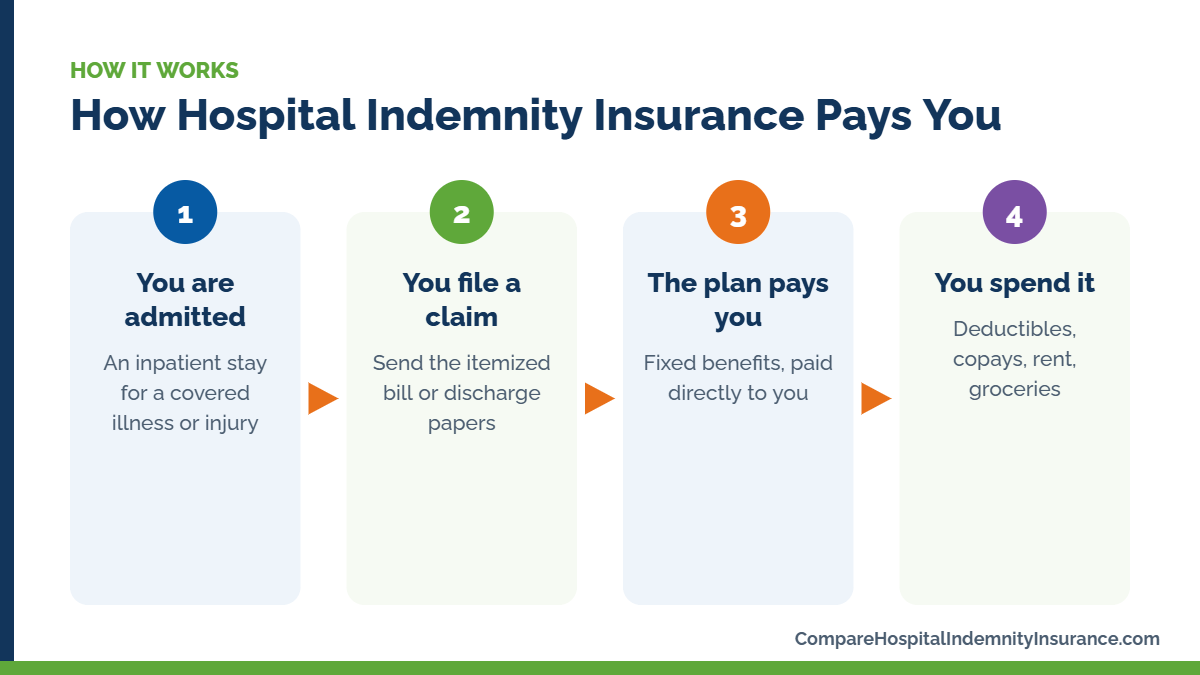
The two are partners, not rivals. Your health plan pays the hospital. Your hospital indemnity plan pays you, so the deductible, coinsurance and copays do not come out of your savings.
Who Hospital Indemnity Insurance Is For
These plans are sold to adults of every age, both at work and directly to individuals. They make the most sense for people whose health plan leaves a large share of a hospital bill to them.
- ✔
Workers on high-deductible or HSA-eligible employer plans
- ✔
Families on Bronze or Silver ACA Marketplace plans with high out-of-pocket limits
- ✔
Medicare Advantage members who pay a copay for each day in the hospital
- ✔
Self-employed people who lose income when they cannot work
- ✔
Couples planning a pregnancy, once the waiting period has been met
Not sure it makes sense for you? Read is hospital indemnity insurance worth it, and if a baby is in your plans, see hospital indemnity insurance for pregnancy.
Individual vs. Group Hospital Indemnity Insurance
You can buy a plan on your own or through work. Group plans offered as a voluntary employee benefit are often guaranteed issue during open enrollment and are paid through payroll deduction. Individual plans usually ask a few health questions, but you own the policy and keep it if you change jobs. Learn about the different hospital indemnity insurance plans and compare the best hospital indemnity insurance companies.
Waiting Periods and Pre-Existing Conditions
Two rules decide when a plan starts paying. Most individual plans cover accidents right away but have a short waiting period for illnesses, often around 30 days, and a longer one for pregnancy. Most also limit coverage for stays related to a condition you were treated for shortly before buying, usually for the first several months. Employer group plans are often more generous on both counts.
How It Compares to Accident and Critical Illness Insurance
Hospital indemnity insurance pays for a hospital stay, whatever put you there. Accident insurance pays scheduled amounts for injuries, even when you go home the same day. Critical illness insurance pays one lump sum when you are diagnosed with a covered condition such as a heart attack, stroke or cancer. Many families carry two of the three so the gaps overlap.