Speak with a licensed insurance agent

1-888-891-0229

What Does UnitedHealthcare Hospital Indemnity Cover? Paid Events, Exclusions and Definitions

Reviewed by Russell Noga, Licensed Insurance Agent — Last updated November 10, 2026

UnitedHealthcare hospital indemnity covers inpatient hospital confinement from a covered sickness or injury, paying a fixed cash amount for the admission, for each day you stay and extra for intensive care days, with some versions adding emergency room, surgery or wellness benefits. It does not pay for cosmetic treatment, self-inflicted injuries, war, felonies or rehab and custodial stays, and every version limits pre-existing conditions.

Quick look

Check Which Hospital Plans Pay for Your Situation

Enter your ZIP to see hospital indemnity policies offered in your state.

Plan availability, eligibility, and benefits vary by state and policy.

Which rules apply depends on whether you bought a policy yourself or enrolled through work. Individual policies are written by Golden Rule Insurance Company and sold through UnitedHealthOne, while employer plans are certificates issued by UnitedHealthcare Insurance Company. Our UnitedHealthcare hospital indemnity overview covers the product lineup and claim deadlines; this page goes line by line through what each document pays and leaves out.

Every version is a supplemental, limited-benefit policy. It does not replace health insurance and is not minimum essential coverage under the Affordable Care Act. To see how UnitedHealthcare stacks up, browse our ranking of hospital indemnity insurance companies or compare hospital indemnity insurance plans sold in your ZIP code.

Quick answer

UnitedHealthcare hospital indemnity covers hospital admissions, daily inpatient confinement and ICU days caused by a covered illness or injury, and some plans add ER, surgery or wellness benefits. Exclusions such as self-harm, war, cosmetic care and rehab stays apply, and the individual and employer versions treat pregnancy and mental health very differently.

Two Sets of Paperwork, Two Coverage Lists

UnitedHealthcare does not publish one master list of covered events. The answer sits in whichever document you hold, and the two main families were written by different insurance companies for different buyers.

Individual: Health ProtectorGuard
Golden Rule policy form HPG3-GRI, sold to adults 18 to 64 who answer health questions. Its outline of coverage (brochure 46034-G-1122) lists the benefits and 25 exclusion categories used on this page.
Employer: Hospital Indemnity Protection Plan
UnitedHealthcare Insurance Company group forms UHIHIP-POL and UHIHIP-CERT. The employer picks the benefit option, and each worker gets a certificate of coverage.
Medicare-age: AdvantageGuard
A separate Golden Rule policy for applicants 60 through 90, mentioned only so it is not confused with the two plans above.

Golden Rule also sells Hospital SafeGuard in some states. The individual examples below use Health ProtectorGuard because its full exclusion list is in a public brochure.

What a Health ProtectorGuard Policy Pays For

Health ProtectorGuard is the broadest individual hospital product UnitedHealthOne sells. The outline of coverage describes these covered events, each paying a fixed amount set by the level you buy.

Covered events in the individual outline of coverage
  • ✔
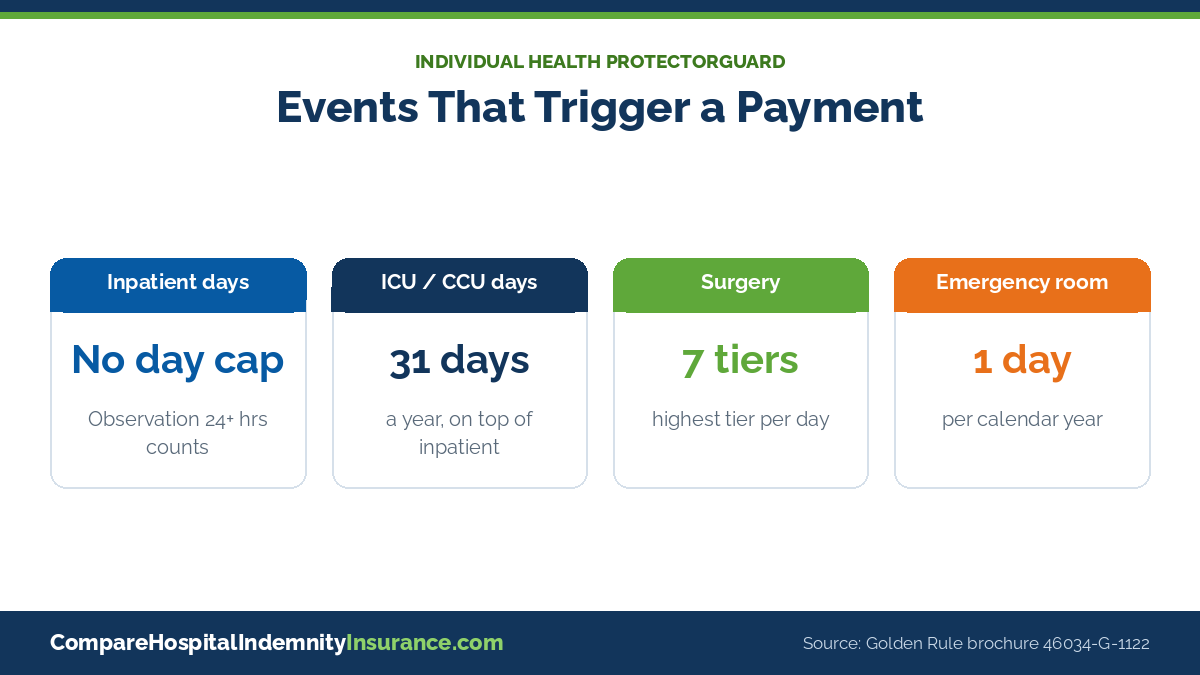
    Inpatient confinement for illness or injury, paid per day with no yearly day limit, counting Observation Unit stays of 24 hours or more
  • ✔
    A hospital admission benefit for the first inpatient day
  • ✔
    Intensive care or cardiac care unit days, paid on top of the inpatient benefit for up to 31 days a calendar year
  • ✔
    Surgery in seven tiers by CPT code, inpatient or outpatient, paying only the highest tier when several surgeries happen the same day
  • ✔
    Outpatient facility days, emergency room visits and up to two ambulance trips a calendar year
  • ✔
    Wellness and preventive benefits after a 30-day waiting period, with no wait in Maryland or Utah

The injury side of the inpatient benefit doubles in the second policy year, but sickness stays pay the same as in year one.

What does UnitedHealthcare hospital indemnity cover: inpatient days, ICU days, surgery tiers and ER visits under the individual Health ProtectorGuard policy

What One Employer’s UnitedHealthcare Certificate Pays

Employers choose group benefits, so amounts differ by company. As one real example, the 2025 certificate UnitedHealthcare issued to Synopsys, Inc. employees offers two options.

Benefit Option 1 Option 2 Limit in the certificate
Hospital admission $1,000 $2,000 Once per period of confinement
Daily hospital confinement $100 a day $200 a day Up to 365 days a plan year
ICU admission $1,000 $2,000 Once per ICU period of confinement
Daily ICU confinement $100 a day $200 a day Up to 365 days a plan year
Inpatient mental or nervous disorder treatment $100 a day $200 a day 30 days a plan year, 300 days lifetime
Inpatient drug and alcohol treatment $100 a day $200 a day 30 days a plan year, 300 days lifetime
Wellness rider (one screening test) $50 $50 Once a calendar year

Source: UnitedHealthcare Insurance Company group certificate for Synopsys, Inc., effective January 1, 2025. One employer’s plan shown as an example; your certificate sets your own amounts.

Other employer designs:

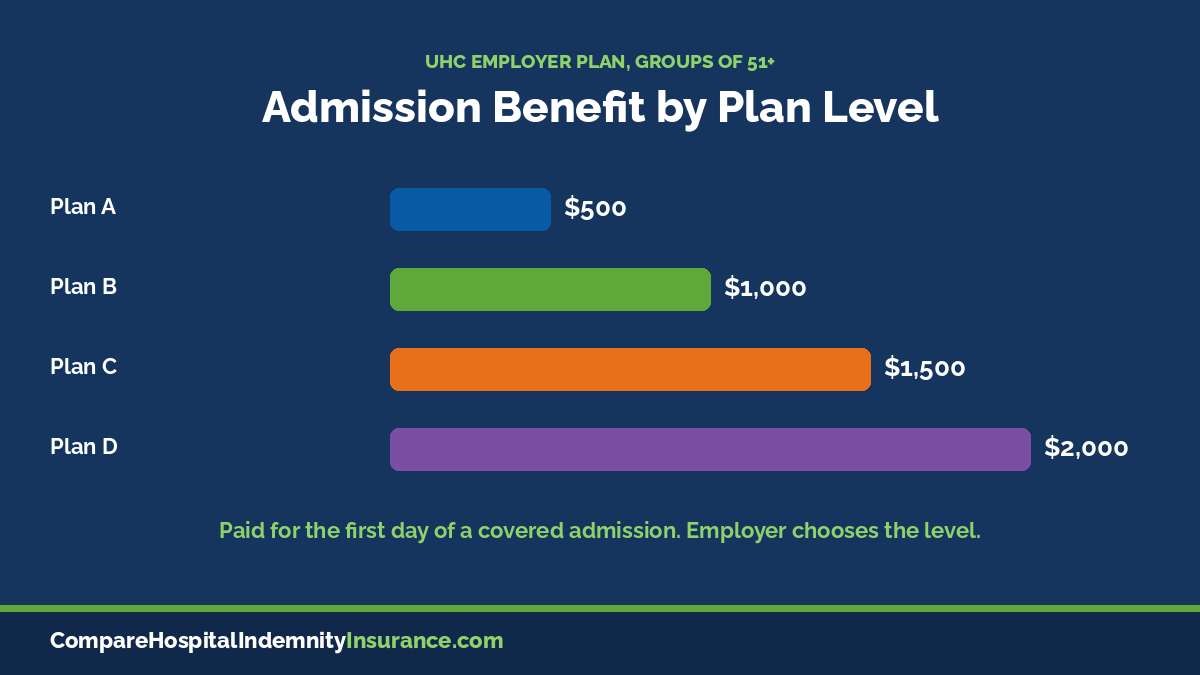
A UnitedHealthcare brochure for groups of 51 or more lists four plan levels, plus an enhanced version that adds a $100 emergency room benefit and lodging and transportation benefits.

Individual vs Employer UHC Coverage, Side by Side

No UnitedHealthcare page compares the coverage rules of its individual and group hospital products, so this table was assembled from the Health ProtectorGuard outline of coverage and the Synopsys group certificate.

Coverage question Health ProtectorGuard (individual) Employer certificate (Synopsys 2025)
Childbirth admission Excluded, except complications of pregnancy or where state law requires Paid: the certificate defines sickness to include pregnancy
Inpatient mental health care Excluded in most states (not in Maryland) Paid at the daily amount, 30 days a plan year
Inpatient substance use treatment Excluded Paid at the daily amount, 30 days a plan year
Observation stays Count as inpatient at 24 hours or more Not covered without a room and board charge
Emergency room only Paid one day a calendar year Not covered
Surgery Seven-tier surgery benefit No surgery benefit in the schedule
Weekend admission Excluded on Friday or Saturday unless an emergency Not on the certificate’s exclusion list
Who can be covered Adults 18 to 64, children to 26 Actively at work employees, spouses, children under 26

Our comparison of Golden Rule brochure 46034-G-1122 (form HPG3-GRI) and a 2025 UnitedHealthcare group certificate. State variations apply to both.

The pattern

The individual policy reaches further into outpatient care, while the employer certificate is the better fit for a planned delivery, a psychiatric admission or an inpatient addiction program.

Russell Noga, licensed insurance agent

Claim-day tip

A UnitedHealthcare employer certificate pays the daily hospital benefit only for an admission of at least 20 hours that carries a full day’s room and board charge. The itemized hospital bill shows that room and board line, so a copy of it sent with the claim form answers the inpatient question before it is asked.

Russell Noga, Licensed Insurance Agent

How UnitedHealthcare Defines Inpatient, ICU and Hospital

Many denied hospital indemnity claims turn on a definition, not an exclusion. The Synopsys group certificate spells out the terms that decide whether a day pays.

1
Inpatient means 20 hours plus room and board. The certificate requires an admission of at least 20 hours with a full day’s room and board charge. ER visits, outpatient treatment and observation stays without that charge do not qualify.
2
An ICU must be a true critical care unit. It needs full-time nursing, full-time physician direction and critical care equipment. Step-down, progressive care and intermediate care units are not counted as ICU.
3
A hospital must mainly treat inpatients. It must be licensed, have registered nurses on duty around the clock and be accredited. Nursing homes, rehab centers and custodial facilities do not count.
4
Stays less than 90 days apart can merge. Confinements for the same or related causes count as one period, so the admission benefit is not paid twice.

The individual outline uses a different line: an Observation Unit stay of 24 hours or more counts as inpatient time. To estimate what a stay would actually pay under either version, our guide on how much hospital indemnity pays walks through the math.

Exclusions Written Into UnitedHealthcare Documents

Shared by both versions

  • Acts of war, declared or undeclared, and active military service
  • Intentionally self-inflicted injury and taking part in a riot
  • Committing or attempting a felony
  • Intoxication or controlled substances not taken as prescribed
  • Cosmetic treatment, though the group certificate allows surgery to repair an injury
  • Treatment outside the United States, with an emergency exception on the individual policy
  • Certain racing and aviation activities, worded differently in each document
  • Routine newborn nursery or well-baby care during the birth stay

Only in the individual Health ProtectorGuard outline

State softening of the rules
✔

Florida drops the weekend admission exclusion
✔

Texas and Virginia pay the first Friday or Saturday of a stay that starts on one of those days
✔

Maryland covers mental disorders and substance abuse treatment
✔

Colorado drops the symptoms test from the pre-existing rule
Extra individual exclusions
✕

Infertility treatment and abortion except to save the mother’s life
✕

Experimental or investigational treatment
✕

Services not medically necessary or performed by a family member
✕

Losses while incarcerated or driving a taxi for pay

The group certificate adds its own exclusions, including vasectomy or tubal ligation reversal, IVF, paid professional athletics and injuries covered by workers’ compensation.


UnitedHealthcare hospital indemnity employer plan admission benefit by plan level A through D for groups of 51 or more

Hospital Indemnity Quotes

Call a Licensed Agent Now

A licensed agent can check which hospital plans in your state cover childbirth, observation stays and mental health care.

☎ 1-888-891-0229

No obligation to enroll

Pregnancy, Pre-Existing Conditions and Age Rules

The biggest coverage gap between the two UnitedHealthcare versions is maternity. A Health ProtectorGuard policy excludes pregnancy and childbirth except for complications. The Synopsys group certificate counts pregnancy as a sickness, covers newborns from live birth for 31 days, and keeps that coverage only if a written request and any premium reach the insurer in time. Our guide to whether hospital indemnity covers childbirth compares that rule across carriers.

Limits from the UHC documents
12 months
individual pre-existing look-back and limit in most states
12/12
standard pre-existing exclusion on employer brochures
Age 65
when individual coverage ends for the primary insured
Age 75
when employer portability coverage ends

Pre-existing wording also shifts by state. Nebraska, North Carolina and Pennsylvania look only at care recommended or received in the look-back period, and Missouri waives the limit for a child placed for adoption. UnitedHealthcare says its group product is not sold in every state, and the individual brochure points to state availability rules rather than a map.

No-cost comparison

Line Up UHC Exclusions Against Other Carriers

Compare how other insurers treat pregnancy, mental health and observation stays.

Plan availability, eligibility, and benefits vary by state and policy.

UnitedHealthcare Hospital Coverage: Common Questions

➤ Does UnitedHealthcare hospital indemnity pay for an emergency room visit?

Only some versions do. Health ProtectorGuard pays an ER benefit for one day a calendar year, and some enhanced employer designs add a $100 ER benefit. The Synopsys group certificate does not pay for an ER-only visit.

➤ Will a UHC hospital plan pay if I am kept under observation?

It depends on the document. The individual Health ProtectorGuard outline counts an Observation Unit stay of 24 hours or more as inpatient time, while the group certificate reviewed here excludes observation stays that carry no room and board charge.

➤ Is a step-down unit counted as intensive care?

Not under the UnitedHealthcare group certificate reviewed here, which leaves step-down, progressive care and intermediate care units out of its ICU definition.

➤ Are psychiatric hospital stays covered?

The employer certificate pays a daily benefit for inpatient mental or nervous disorder treatment for up to 30 days a plan year. Health ProtectorGuard excludes mental disorder treatment in most states, with Maryland as the main exception.

➤ Does UnitedHealthcare hospital indemnity cover rehab after surgery?

No. Both the individual outline and the group certificate exclude confinement mainly for rehabilitation, custodial or nursing care.

➤ Can I get a payment for a hospital stay while traveling abroad?

The individual policy excludes services outside the United States except emergency treatment. The group certificate excludes treatment outside the United States and its territories.

➤ Does a UnitedHealthcare hospital indemnity plan count as health insurance?

No. Both versions are limited-benefit fixed indemnity coverage that pays set amounts regardless of your bills and is not minimum essential coverage.

Free Coverage Check

Call a Licensed Agent Now

Have your UnitedHealthcare certificate or outline of coverage handy to compare exclusions with other carriers.

☎ 1-888-891-0229

No obligation to enroll

Russell Noga, licensed insurance agent

About the Author: Russell Noga

Russell Noga is a licensed insurance agent and the founder of ZRN Health & Financial Services, LLC. He has helped people compare health and supplemental insurance for more than 16 years and reviews every page on Compare Hospital Indemnity Insurance before it is published. Learn more about us or read our Editorial Standards.

CompareHospitalIndemnityInsurance.com is operated by ZRN Health & Financial Services, LLC, a Texas limited liability company based in Austin, Texas. We are not connected with or endorsed by any government agency.